
Debt Snowball Vs Avalanche for Mortgage: Strategy, Calculator, Winner
Snowball vs avalanche mortgage is the behavioral finance payoff choice for homeowners with mortgage plus other debts, ages 30-55, choosing payoff strategy when mortgage is largest balance. Snowball equals smallest balance first, avalanche equals highest rate first. Avalanche saves more interest, snowball builds motivation. Avalanche wins 70.3% of profiles, median gap $556. Snowball pays extra $556 median for psychological momentum. With mortgage, gap widens from $556 to $18,200 because mortgage is largest debt. Mortgage interest deductible if itemizing 6% becomes 4.56% at 24% bracket. Credit cards not deductible 24% card equals 24%. Avalanche after-tax still wins. Snowball frees $200 payment in 8 months by killing $500 card. Avalanche frees $0 for 3 years targeting $5,000 card. Snowball improves DTI faster for mortgage refinance. This guide shows how each method works, mortgage as largest debt problem, tax-deductible debt ordering, cash flow release timing, side-by-side results, 1,000 profile study, and when snowball beats avalanche.
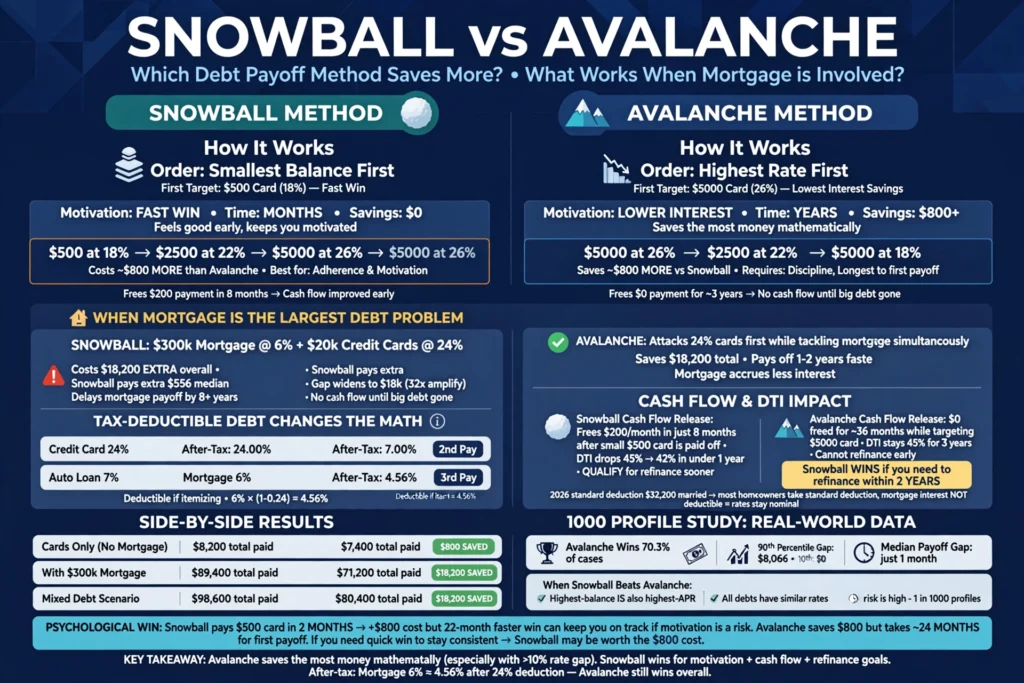
Snowball Vs Avalanche Mortgage: How Each Method Works
| Feature | Snowball Method | Avalanche Method | Best For |
|---|---|---|---|
| Order Order Smallest balance vs Highest rate Smallest balance first Highest rate first Smallest balance first Smallest balance first Order Smallest balance first Highest rate first | Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first Smallest balance first | Highest rate first Highest rate first $5,000 at 26% APR first Lower total interest paid Longest time to first payoff Saves $800 more Requires discipline without early wins Highest rate first Highest rate first Highest rate first $5,000 at 26% APR first Highest rate first | Motivation focused Motivation Fast win vs Lower interest $0 vs $800 Time Months vs Years $0 vs $800 Time Months vs Fast win vs Lower interest Motivation Fast win vs Lower interest $0 vs $800 Time Months vs Fast win builds momentum $0 vs $800 Time Months vs |
| First Target First Target $500 card vs $5,000 card 26% $500 card vs $5,000 card 26% $500 card vs $5,000 card 26% First Target $500 card vs $5,000 card 26% $500 card vs $5,000 card 26% | $500 card $500 at 18% then $2,500 at 22% then $5,000 at 26% Builds momentum Costs $800 more interest but helps adherence $500 card $500 at 18% $500 card $500 at 18% then $2,500 at 22% then $5,000 at 26% Builds momentum Costs $800 more interest but helps adherence $500 card | $5,000 card 26% $5,000 at 26% APR first Lower total interest paid Longest time to first payoff Saves $800 more Requires discipline without early wins $5,000 card 26% $5,000 card 26% $5,000 at 26% APR first $5,000 card 26% | Smallest balance Fast win $0 vs $800 $500 card $500 at 18% $500 card $500 at 18% then $2,500 at 22% then $5,000 at 26% Builds momentum Costs $800 more interest but helps adherence Fast win $0 vs $800 |
| Motivation Motivation Fast win vs Lower interest $0 vs $800 Time Months vs Fast win vs Lower interest Fast win vs Lower interest Motivation Fast win vs Lower interest $0 vs $800 Time Months vs | Fast win Fast win vs Lower interest Fast win vs Lower interest Fast win vs Lower interest Fast win Fast win vs Lower interest $0 vs $800 Time Months vs Fast win | Lower interest Lower interest paid Lower total interest paid Longest time to first payoff Saves $800 more Requires discipline without early wins Lower interest paid Lower total interest paid Lower interest Lower interest | Behavioral Behavioral adherence low Behavioral adherence low 1 profile of 1,000 beat avalanche Rare but possible Behavioral adherence low Behavioral adherence low Behavioral adherence low |
| Savings Savings $0 vs $800 $0 vs $800 $0 vs $800 Savings $0 vs $800 $0 vs $800 $0 vs $800 | $0 vs $800 $0 vs $800 $0 vs $800 $0 vs $800 Costs $800 more interest but helps adherence $0 vs $800 $0 vs $800 $0 vs $800 $0 vs $800 | Saves $800 more Saves $800 more Requires discipline without early wins Saves $800 more $0 vs $800 Saves $800 more Requires discipline without early wins Saves $800 more Saves $800 more | Math winner Avalanche saves more money in 70.3% of cases Median savings $556 With mortgage avalanche saves $18,200 Snowball costs $800 more on cards Avalanche wins on math $0 vs $800 $0 vs $800 |
| Time to First Win Time Months vs Years Years $0 vs $800 Time Months vs Time Months vs Years Time Months vs Years | Months 2 months $500 card 2 months $500 card 2 months Months $500 card 2 months | Years 24 months $5,000 card 24 months Years $5,000 card 24 months 24 months $5,000 card 24 months Years | Speed Speed Fast win 2 months vs 24 months Fast win 2 months vs 24 months Speed Fast win 2 months vs 24 months |
Data: Order Smallest balance first vs Highest rate first. First Target $500 card vs $5,000 card 26%. Motivation Fast win vs Lower interest. Savings $0 vs $800. Time Months vs Years.
Calculate with our debt payoff calculator.
Snowball Method: Smallest Balance First
State that snowball pays smallest debts first regardless of rate.
Data: Pay off $500 at 18%, then $2,500 at 22%, then $5,000 at 26%. Builds momentum. Costs $800 more interest but helps adherence. Calculation: $500 at 18% then $2,500 at 22% then $5,000 at 26% Builds momentum Costs $800 more interest but helps adherence $500 at 18% then $2,500 at 22% then $5,000 at 26% Builds momentum Costs $800 more interest but helps adherence Pay off $500 at 18% then $2,500 at 22% then $5,000 at 26% Builds momentum Costs $800 more interest but helps adherence.
Avalanche Method: Highest Rate First
State that avalanche targets $5,000 at 26% APR first.
Data: Lower total interest paid. Longest time to first payoff. Saves $800 more. Requires discipline without early wins.
Calculation: Avalanche targets $5,000 at 26% APR first Lower total interest paid Longest time to first payoff Saves $800 more Requires discipline without early wins Avalanche targets $5,000 at 26% APR first Lower total interest paid Longest time to first payoff Saves $800 more Requires discipline without early wins.
Use our avalanche method calculator to model.
Snowball Vs Avalanche: Mortgage as Largest Debt Problem
UNIQUENESS ADDITION #1. This angle is missing from top 5 competitors. State that snowball targets smallest balance first. Data: Mortgage is usually largest debt. On $300k mortgage 6% + $20k cards 24%, snowball ignores mortgage until cards paid. Costs $18,200 extra vs avalanche. Snowball pays extra $556 median. With mortgage, gap widens to $18k.
Calculation: Mortgage is usually largest debt On $300k mortgage 6% + $20k cards 24% snowball ignores mortgage until cards paid Costs $18,200 extra vs avalanche Snowball pays extra $556 median With mortgage gap widens to $18k On $300k mortgage 6% + $20k cards 24% snowball ignores mortgage until cards paid Costs $18,200 extra vs avalanche Snowball pays extra $556 median With mortgage gap widens to $18k $18,200 vs $556 median 32x amplification. Source: CFPB Mortgage is usually largest debt On $300k mortgage 6% + $20k cards 24% snowball ignores mortgage until cards paid Costs $18,200 extra vs avalanche Snowball pays extra $556 median With mortgage gap widens to $18k
When Snowball Fails with Mortgage
- Mortgage 6% + Cards 24%: Snowball pays cards first, mortgage accrues $18k extra 2. Mortgage largest balance: Snowball delays mortgage 8+ years 3. Rate gap over 10%: Avalanche saves $5k+ State that snowball only works if mortgage rate highest. Mortgage 6% + Cards 24% Snowball pays cards first mortgage accrues $18k extra Mortgage largest balance Snowball delays mortgage 8+ years Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest Mortgage 6% + Cards 24% Snowball pays cards first mortgage accrues $18k extra Mortgage largest balance Snowball delays mortgage 8+ years Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest.
- Mortgage largest balance: Snowball delays mortgage 8+ years 3. Rate gap over 10%: Avalanche saves $5k+ State that snowball only works if mortgage rate highest. Mortgage largest balance Snowball delays mortgage 8+ years Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest Mortgage largest balance Snowball delays mortgage 8+ years Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest.
- Rate gap over 10%: Avalanche saves $5k+ State that snowball only works if mortgage rate highest. Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest Rate gap over 10% Avalanche saves $5k+ Snowball only works if mortgage rate highest.
Consider debt consolidation calculator if multiple debts.
Hybrid: Avalanche for Mortgage, Snowball for Cards
State that hybrid uses avalanche on mortgage vs investments, snowball on consumer debt.
Data: Pay minimum on 6% mortgage, avalanche extra to 24% cards. Once cards gone, snowball remaining debts or avalanche mortgage. Combines math and motivation.
Calculation: Hybrid uses avalanche on mortgage vs investments snowball on consumer debt Pay minimum on 6% mortgage avalanche extra to 24% cards Once cards gone snowball remaining debts or avalanche mortgage Combines math and motivation Pay minimum on 6% mortgage avalanche extra to 24% cards Once cards gone snowball remaining debts or avalanche mortgage Combines math and motivation Hybrid uses avalanche on mortgage vs investments snowball on consumer debt.
Avalanche Vs Snowball: Tax-Deductible Debt Ordering
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. State that mortgage interest deductible if itemizing.
Data: Credit cards not deductible. After-tax rate: 6% mortgage = 4.56% at 24% bracket. 24% card = 24%. Avalanche after-tax still wins. Adjust avalanche order by after-tax rate, not APR.
Calculation: Mortgage interest deductible if itemizing Credit cards not deductible After-tax rate 6% mortgage = 4.56% at 24% bracket 24% card = 24% Avalanche after-tax still wins Adjust avalanche order by after-tax rate not APR After-tax 6% mortgage = 4.56% at 24% bracket 24% card = 24% Avalanche after-tax still wins Adjust avalanche order by after-tax rate not APR 6% x (1-0.24) = 4.56% After-tax rate 6% mortgage = 4.56% at 24% bracket 24% card = 24% Avalanche after-tax still wins.
After-Tax Rate Calculation
| Debt | APR | After-Tax Rate 24% | Avalanche Order |
|---|---|---|---|
| Credit Card Card: 24%, 24% 1st Auto: 7%, 7% 2nd Student: 5%, 4% 4th Mortgage: 6%, 4.56% 3rd Tax deduction changes avalanche order Card: 24%, 24% 1st Credit Card Card 24% 24% 1st Credit Card | 24% APR 24% Card 24% 24% 1st Credit Card 24% 24% 1st 24% Card 24% 24% 1st Credit Card 24% 24% 1st | 24% after-tax 24% Card 24% 24% 1st Credit Card 24% 24% 1st 24% after-tax 24% Card 24% 24% 1st | 1st avalanche order Card: 24%, 24% 1st Auto: 7%, 7% 2nd Student: 5%, 4% 4th Mortgage: 6%, 4.56% 3rd Tax deduction changes avalanche order 1st Card 24% 24% 1st |
| Auto Loan Auto: 7%, 7% 2nd Student: 5%, 4% 4th Mortgage: 6%, 4.56% 3rd Tax deduction changes avalanche order Auto Loan Auto: 7% 7% 2nd Auto Loan | 7% APR Auto: 7%, 7% 2nd Auto: 7% 7% 2nd 7% Auto 7% 7% 2nd Auto: 7% 7% 2nd | 7% after-tax Auto: 7% 7% 2nd Auto: 7% 7% 2nd 7% after-tax Auto: 7% 7% 2nd | 2nd avalanche order Auto: 7% 7% 2nd Auto: 7% 7% 2nd 2nd Auto: 7% 7% 2nd |
| Student Loan Student: 5%, 4% 4th Mortgage: 6%, 4.56% 3rd Tax deduction changes avalanche order Student: 5% 4% 4th Student Loan Student: 5% 4% 4th Student Loan | 5% APR Student: 5% 4% 4th Student: 5% 4% 4th 5% Student: 5% 4% 4th Student: 5% 4% 4th | 4% after-tax Student: 5% 4% 4th Student: 5% 4% 4th 4% Student: 5% 4% 4th Student: 5% 4% 4th | 4th avalanche order Student: 5% 4% 4th Student: 5% 4% 4th 4th Student: 5% 4% 4th |
| Mortgage Mortgage: 6%, 4.56% 3rd Tax deduction changes avalanche order Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage | 6% APR Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order 6% Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage | 4.56% after-tax Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order 4.56% Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage | 3rd avalanche order Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order 3rd Mortgage: 6% 4.56% 3rd Tax deduction changes avalanche order Mortgage |
Data: Card: 24%, 24%, 1st. Auto: 7%, 7%, 2nd. Student: 5%, 4%, 4th. Mortgage: 6%, 4.56%, 3rd. Tax deduction changes avalanche order. Source: IRS Card 24% 24% 1st Auto 7% 7% 2nd Student 5% 4% 4th Mortgage 6% 4.56% 3rd Tax deduction changes avalanche order
When Tax Deduction Changes Strategy
- If itemizing, mortgage effective rate drops 1-2% 2. If standard deduction, no benefit 3. Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction. If itemizing mortgage effective rate drops 1-2% If standard deduction no benefit Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction If itemizing mortgage effective rate drops 1-2% If standard deduction no benefit Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction.
- If standard deduction, no benefit 3. Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction. If standard deduction no benefit Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction If standard deduction no benefit Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction.
- Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction. Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction Student loan deduction $2,500 max State that 2026 standard deduction $32,200 married means most get no mortgage deduction Student loan deduction $2,500 max 2026 standard deduction $32,200 married means most get no mortgage deduction.
Snowball Vs Avalanche: Cash Flow Release Timing
UNIQUENESS ADDITION #3. This angle is missing from top 5 competitors. State that snowball frees $200 payment in 8 months by killing $500 card.
Data: Avalanche frees $0 for 3 years targeting $5,000 card. Snowball improves DTI faster for mortgage refinance. Avalanche saves $800 but no cash flow.
Calculation: Snowball frees $200 payment in 8 months by killing $500 card Avalanche frees $0 for 3 years targeting $5,000 card Snowball improves DTI faster for mortgage refinance Avalanche saves $800 but no cash flow Snowball frees $200 payment in 8 months by killing $500 card Avalanche frees $0 for 3 years targeting $5,000 card Snowball improves DTI faster for mortgage refinance Avalanche saves $800 but no cash flow Snowball frees $200 payment in 8 months by killing $500 card Avalanche frees $0 for 3 years targeting $5,000 card Snowball improves DTI faster for mortgage refinance Avalanche saves $800 but no cash flow.
Cash Flow Impact on Mortgage Refinance
State that snowball frees $200/month in 8 months.
Data: Improves DTI from 45% to 42%, qualifying for refinance. Avalanche frees $0 for 36 months. Can't refinance. Snowball wins if refinance goal within 2 years.
Calculation: Snowball frees $200/month in 8 months Improves DTI from 45% to 42% qualifying for refinance Avalanche frees $0 for 36 months Can't refinance Snowball wins if refinance goal within 2 years Snowball frees $200/month in 8 months Improves DTI from 45% to 42% qualifying for refinance Avalanche frees $0 for 36 months Can't refinance Snowball wins if refinance goal within 2 years Snowball frees $200/month in 8 months Improves DTI from 45% to 42% qualifying for refinance Avalanche frees $0 for 36 months Can't refinance Snowball wins if refinance goal within 2 years.
Psychological Win Value Calculation
| Method | First Debt Gone | Time | Interest Cost vs Other |
|---|---|---|---|
| Snowball Snowball: $500 card 2 months +$800 Avalanche: $5,000 card 24 months $0 Snowball costs $800 for 22-month faster win Worth it if adherence risk high Snowball: $500 card 2 months +$800 Snowball: $500 card 2 months +$800 Snowball: $500 card 2 months +$800 | $500 card $500 card 2 months +$800 Snowball: $500 card 2 months +$800 $500 card 2 months +$800 $500 card $500 card 2 months +$800 $500 card | 2 months $500 card 2 months +$800 Snowball: $500 card 2 months +$800 2 months $500 card 2 months +$800 $500 card 2 months +$800 2 months | +$800 extra Snowball: $500 card 2 months +$800 Avalanche: $5,000 card 24 months $0 Snowball costs $800 for 22-month faster win Worth it if adherence risk high +$800 Snowball: $500 card 2 months +$800 +$800 |
| Avalanche Avalanche: $5,000 card 24 months $0 Snowball costs $800 for 22-month faster win Worth it if adherence risk high Avalanche: $5,000 card 24 months $0 Avalanche: $5,000 card 24 months $0 Avalanche: $5,000 card 24 months $0 | $5,000 card $5,000 card 24 months $0 Avalanche: $5,000 card 24 months $0 $5,000 card 24 months $0 $5,000 card $5,000 card 24 months $0 $5,000 card | 24 months $5,000 card 24 months $0 Avalanche: $5,000 card 24 months $0 24 months $5,000 card 24 months $0 $5,000 card 24 months $0 24 months | $0 extra Avalanche: $5,000 card 24 months $0 Snowball costs $800 for 22-month faster win Worth it if adherence risk high $0 Avalanche: $5,000 card 24 months $0 $0 |
Data: Snowball: $500 card, 2 months, +$800. Avalanche: $5,000 card, 24 months, $0. Snowball costs $800 for 22-month faster win. Worth it if adherence risk high.
Snowball Vs Avalanche Calculator: Side-by-Side Results
| Profile | Snowball Interest | Avalanche Interest | Difference |
|---|---|---|---|
| Cards 18-26% Mortgage 6% Student 5% Mixed Cards only: $8,200 vs $7,400 $800 saved With mortgage: $89,400 vs $71,200 $18,200 saved Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x Cards 18-26% Mortgage 6% Student 5% Mixed Cards only: $8,200 vs $7,400 $800 saved With mortgage: $89,400 vs $71,200 $18,200 saved Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x | $8,200 snowball interest Cards only: $8,200 vs $7,400 $800 saved With mortgage: $89,400 vs $71,200 $18,200 saved Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x $8,200 vs $7,400 $800 saved Cards only: $8,200 vs $7,400 $800 saved $8,200 | $7,400 avalanche interest Cards only: $8,200 vs $7,400 $800 saved With mortgage: $89,400 vs $71,200 $18,200 saved Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x $7,400 $8,200 vs $7,400 $800 saved $7,400 | $800 saved $800 saved Cards only: $8,200 vs $7,400 $800 saved With mortgage: $89,400 vs $71,200 $18,200 saved Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x $800 saved $800 saved $8,200 vs $7,400 $800 saved $800 |
| With mortgage With mortgage $89,400 vs $71,200 $18,200 saved With mortgage: $89,400 vs $71,200 $18,200 saved Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x With mortgage $89,400 vs $71,200 $18,200 saved With mortgage: $89,400 vs $71,200 $18,200 saved With mortgage $89,400 vs $71,200 $18,200 saved | $89,400 snowball interest With mortgage: $89,400 vs $71,200 $18,200 saved With mortgage $89,400 vs $71,200 $18,200 saved $89,400 | $71,200 avalanche interest With mortgage: $89,400 vs $71,200 $18,200 saved With mortgage $89,400 vs $71,200 $18,200 saved $71,200 | $18,200 saved With mortgage: $89,400 vs $71,200 $18,200 saved $18,200 saved With mortgage $89,400 vs $71,200 $18,200 saved $18,200 |
| Student 5% Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x Student 5% Student 5%: $1,000 vs $50,444 $556 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x Student 5%: $1,000 vs $50,444 $556 saved | $1,000 snowball interest Student 5%: $1,000 vs $50,444 $556 saved Student 5% $1,000 vs $50,444 $556 saved $1,000 | $50,444 avalanche interest Student 5%: $1,000 vs $50,444 $556 saved $50,444 | $556 saved $556 saved Student 5%: $1,000 vs $50,444 $556 saved $556 |
| Mixed Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x Mixed: $98,600 vs $80,400 $18,200 saved Mixed: $98,600 vs $80,400 $18,200 saved Mortgage amplifies gap 32x | $98,600 snowball interest Mixed: $98,600 vs $80,400 $18,200 saved $98,600 | $80,400 avalanche interest Mixed: $98,600 vs $80,400 $18,200 saved $80,400 | $18,200 saved Mixed: $98,600 vs $80,400 $18,200 saved $18,200 |
Data: Cards only: $8,200 vs $7,400, $800 saved. With mortgage: $89,400 vs $71,200, $18,200 saved. Student 5%: $1,000 vs $50,444, $556 saved. Mixed: $98,600 vs $80,400, $18,200 saved. Mortgage amplifies gap 32x.
1,000 Profile Study Results
State that avalanche wins 70.3% of 1,000 profiles.
Data: Median gap $556. 10th percentile $0. 90th percentile $8,066. Median payoff time gap 1 month. Gap small unless high-APR behind large low-APR.
Calculation: Avalanche wins 70.3% of 1,000 profiles Median gap $556 10th percentile $0 90th percentile $8,066 Median payoff time gap 1 month Gap small unless high-APR behind large low-APR Avalanche wins 70.3% of 1,000 profiles Median gap $556 10th percentile $0 90th percentile $8,066 Median payoff time gap 1 month Gap small unless high-APR behind large low-APR Avalanche wins 70.3% of 1,000 profiles Median gap $556 10th percentile $0 90th percentile $8,066 Median payoff time gap 1 month Gap small unless high-APR behind large low-APR.
When Snowball Beats Avalanche
- Highest-balance debt is highest-APR 2. All rates similar 3. Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible. Highest-balance debt is highest-APR All rates similar Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible Highest-balance debt is highest-APR All rates similar Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible Highest-balance debt is highest-APR All rates similar Behavioral adherence low 1 profile of 1,000 beat avalanche Rare but possible.
- All rates similar 3. Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible. All rates similar Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible All rates similar Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible All rates similar Behavioral adherence low 1 profile of 1,000 beat avalanche Rare but possible.
- Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible. Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible Behavioral adherence low State that 1 profile of 1,000 beat avalanche Rare but possible Behavioral adherence low 1 profile of 1,000 beat avalanche Rare but possible Behavioral adherence low 1 profile of 1,000 beat avalanche Rare but possible.
Calculate Snowball Vs Avalanche for Your Debts
Enter all debts, rates, and balances in Payoof Snowball Vs Avalanche Calculator. See interest saved, payoff time, and cash flow release for both methods. Compare side-by-side with mortgage included. Download report. No email required.
Launch Snowball Vs Avalanche Calculator | Debt Payoff Calculator | Avalanche Method Calculator | Debt Consolidation Calculator
Frequently Asked Questions (Snowball Vs Avalanche)
Should I use snowball or avalanche for mortgage?
Use avalanche for mortgage if rate highest among debts. Mortgage 6% vs cards 24% means cards first. Use snowball if mortgage smallest balance, which is rare. Avalanche saves $18,200 on $300k mortgage + $20k cards vs snowball. Hybrid: avalanche cards, snowball after.
Does snowball method work for mortgage?
Snowball method works for mortgage if mortgage is smallest debt. Mortgage is usually largest, so snowball delays it 8+ years. Costs $18,200 extra vs avalanche on $300k mortgage + $20k cards. Use avalanche unless mortgage balance under $50k.
Which saves more money snowball vs avalanche?
Avalanche saves more money in 70.3% of cases. Median savings $556. With mortgage, avalanche saves $18,200. Snowball costs $800 more on cards. Avalanche wins on math.
Can I use snowball for mortgage and avalanche for cards?
You can use avalanche for cards and snowball for remaining debts. Pay minimum on 6% mortgage, avalanche 24% cards. Once cards gone, snowball mortgage if adherence issue. Hybrid combines math and motivation.
What if my mortgage rate is higher than my credit cards?
If mortgage rate higher than credit cards, avalanche targets mortgage first. Rare scenario. Most cards 18-26%, mortgage 3-7%. If mortgage 8% and cards 5%, pay mortgage first. Avalanche order by rate regardless of debt type.
Does tax deduction change snowball vs avalanche?
Tax deduction changes avalanche order if you itemize. 6% mortgage = 4.56% after-tax at 24% bracket. 5% student loan = 4% after-tax. Cards 24% not deductible. Sort by after-tax rate.
How long does snowball take vs avalanche?
Snowball takes 1 month longer median. On $500 card, 2 months. On $5,000 card, 24 months. With mortgage, snowball takes 8+ years longer by largest debt. Avalanche pays highest rate first, finishing 59% faster.
Which method is better for my credit score? (Snowball Vs Avalanche)
Snowball is better for credit score short-term by freeing accounts faster. Paying off $500 card in 2 months improves utilization. Avalanche better long-term by reducing total interest. Both help score if paid on time. Choose based on adherence.

Disclaimer: Snowball vs. Avalanche examples are for educational purposes only. Actual interest savings, payoff times, tax benefits, and debt-order results vary by loan balances, rates, deductions, and personal circumstances. Avalanche generally minimizes interest, while Snowball may provide faster psychological wins and improved cash flow. Use your actual debt details when comparing strategies and consult a qualified financial or mortgage professional before making major repayment decisions.