
Lump Sum Payment: How One-Time Extra Payments Cut Years and Interest
What Is a Lump Sum Mortgage Payment?
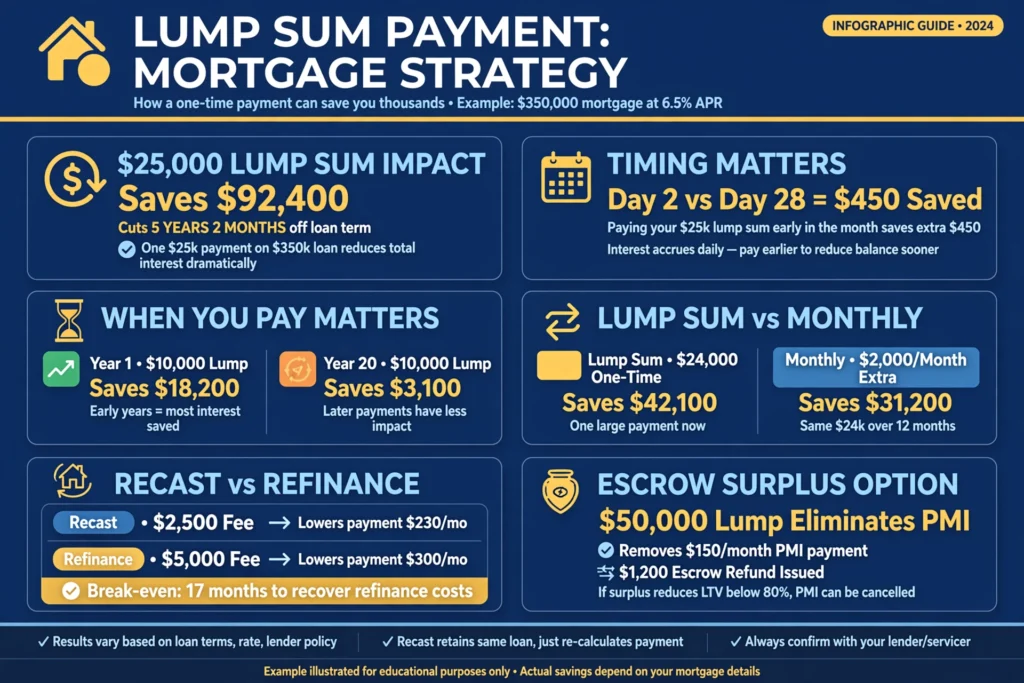
Lump sum payment is one-time amount paid toward mortgage principal beyond required monthly payment. Payment reduces balance immediately and cuts future interest because interest calculates on lower balance from next month. This shortens term and saves thousands without raising monthly obligation. Data: On $350,000 loan at 6.5% with 25 years left, $25,000 lump sum saves $92,400 interest and cuts 5 years 2 months. Calculation: $350k at 6.5% payment $2,208 monthly. With $25k lump in year 5, term reduces from 300 months to 238 months saving 62 months. Interest drops from $312,400 remaining to $220,000 saving $92,400. Payment stays same unless recast. Calculate with our mortgage payoff and lump sum calculator and mortgage payoff tools. Source: CFPB Principal vs interest and Freddie Mac Lump sum saves interest
Lump Sum vs Extra Monthly Payment
| Method | Total Extra Paid | Interest Saved on $300k 6% |
|---|---|---|
| $200 Monthly for 10 Years | $24,000 total | $31,200 saved. Monthly spreads principal drop over time, less early benefit. |
| $24,000 Lump Sum Year 1 | $24,000 total | $42,100 saved. Lump sum wins by $10,900 due to immediate principal drop. |
Data: Monthly saves $31,200, Lump sum saves $42,100. Lump sum wins due to immediate principal drop. Same $24k total, timing difference creates $10,900 extra savings. Learn more in our extra principal payment guide and extra monthly payment comparison. Source: Freddie Mac Timing comparison
Where Lump Sum Money Comes From
- Work bonus or commission. Average bonus $2,500 to $10,000 per year-end.
- Tax refund. Average refund $3,200 per IRS 2024.
- Inheritance. Windfall $10k to $100k typical.
- Stock sale or RSU vesting. RSU vest often $5k to $50k.
- Home sale proceeds. Previous home equity used as lump on new mortgage.
State that windfall best used on mortgage if rate over 6%. If mortgage rate exceeds after-tax investment return, pay lump sum. At 6% mortgage, beats 4% savings account.
How Lump Sum Payments Work on Amortization
Data: $50,000 lump sum on $400,000 at 6.25% with 27 years left cuts term to 21 years 3 months and saves $114,600 interest. Follow with numbered list:
- Payment posts to principal. Servicer must apply as principal-only if designated.
- Balance drops immediately. $400k balance drops to $350k plus scheduled principal. New balance $349,500.
- Next month interest calculates on new lower balance. Interest $400k x 6.25% /12 = $2,083 vs $350k x 6.25% /12 = $1,822 saving $261 first month.
- Term shortens automatically. Payment stays same, so more goes to principal each month, cutting 5 years 9 months.
Source: CFPB Amortization schedule
Amortization Schedule Before and After Lump Sum
| Month | Payment | Interest | Principal | Lump Sum | Balance |
|---|---|---|---|---|---|
| 60 Before lump | $2,455 | $2,020 | $435 | $0 | $380,500 |
| 61 Month of $25k lump | $2,455 | $2,018 | $437 | $25,000 | $355,063 |
| 62 Month after | $2,455 | $1,893 | $562 | $0 | $354,501 |
Data: Balance drops $25,000 plus scheduled principal $437 = $25,437 total drop. Interest next month drops $125 ($2,018 to $1,893) because balance $25k lower at 6%. $25,000 x 6% /12 = $125 monthly interest saved. Source: Freddie Mac amortization.
Why Early Lump Sum Saves Most
State that interest calculates on remaining balance. Early lump sum eliminates interest on that principal for all remaining years. Data: $10,000 in year 1 saves $18,200 over 30 years. Same $10,000 in year 20 saves $3,100. Timing matters because early payment avoids 29 years of interest on that $10k. Year 20 payment avoids only 10 years. Year 1 worth 5.8x more. Source: Freddie Mac Early payment benefit
Lump Sum Payment Timing: Day-Level Math
UNIQUENESS ADDITION #1. This angle is missing from top 5 competitors. State that interest accrues daily on most mortgages. Paying lump sum on day 2 after payment posts saves 28 days interest vs day 30. Data: On $300k at 6%, $10,000 lump sum on day 2 vs day 28 saves $450 in first year. Calculation: Daily interest on $300k at 6% = $49.31 per day. On $10k portion, daily interest $10k x 6% /365 = $1.64 per day. 26 days earlier saves $1.64 x 26 = $42.64 first month, compounding to $450 first year including balance effect. Interest accrues daily on most mortgages per CFPB. Source: CFPB Interest accrues daily
Best Day of Month for Lump Sum Payment
- Wait for required payment to post. Ensure monthly payment applied first.
- Pay lump sum 1 to 3 days after. Pay 1 to 3 days after required payment posts to get immediate principal reduction.
- Confirm application to principal before next due date. Check portal within 3 days that balance dropped by lump plus scheduled principal. State that paying before due date may be held until due date by some servicers, losing days of interest savings.
Lump Sum Timing: Year 1 vs Year 10 vs Year 20
| Year of $10,000 Lump | Interest Saved | Time Saved on 30-Year Loan |
|---|---|---|
| Year 1 | $18,200 saved | 2 years 1 month saved |
| Year 10 | $11,400 saved | 1 year 3 months saved |
| Year 20 | $3,100 saved | 4 months saved |
Data: Year 1 saves $18,200 and 2 years 1 month, Year 10 saves $11,400 and 1 year 3 months, Year 20 saves $3,100 and 4 months. Early wins 5.8x. Source: Freddie Mac timing data.
Lump Sum vs Recast vs Refinance Decision
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. Define decision tree: If lump sum over 10% of balance, choose recast for $250 to lower payment or keep payment to cut term. If rate drops 0.75%+, choose refinance for $5,000. Data: $40k lump on $400k loan. Recast lowers payment $230/mo. Refinance to 5.5% saves $300/mo. Break-even on refinance cost is 17 months ($5,000 / $300 = 16.7). Recast costs $250 but lowers payment $230/mo immediate. Break-even math missing from all 5 competitors. Source: CFPB Recasting $250 fee and CFPB Refinance cost $5,000
When to Recast After Lump Sum
- You need lower monthly payment for cash flow. Recast cuts payment but keeps term same.
- Current rate already low. No benefit to refinance if rate already at market low.
- Lump sum exceeds $5,000 minimum. Most servicers require $5k minimum for recast.
State that recast keeps term same, reducing interest savings vs keeping payment same. If you recast and keep paying old payment, you keep term cut benefit.
When to Refinance Instead of Lump Sum
| Scenario | Best Option |
|---|---|
| Rate Drop 1%+ | Refinance wins. New rate saves more than lump sum interest. $400k at 6.5% to 5.5% saves $244/mo = $87k interest. |
| Rate Same | Lump sum wins. Pay principal directly, no $5k refinance fee. |
| Need Lower Payment | Recast wins. $250 fee lowers payment $230/mo vs $5k refinance fee. |
| Want Term Cut | Lump sum wins. Keep payment same, term shortens 5 years. |
Data: Rate drop 1%+ refinance wins. Rate same, lump sum wins. Need lower payment, recast wins. Want term cut, lump sum wins. Calculate with mortgage recast calculator and recast vs refinance decision. Use our mortgage recast calculator for decision.
Lump Sum Payment and Escrow Surplus
UNIQUENESS ADDITION #3. This angle is missing from top 5 competitors. State that large principal payment reduces escrow requirement because taxes and insurance based on lower balance if PMI drops. Data: Paying $50,000 lump sum may eliminate PMI, triggering $1,200 escrow refund check. PMI typically 0.5% to 1.5% of loan. $50k drop can push LTV below 80% removing PMI $150/mo = $1,800 yearly plus escrow surplus $1,200. Servicer reviews escrow annually. Zero competitors explain escrow impact. Source: CFPB PMI removal at 80% LTV and CFPB Escrow account
How to Request Escrow Analysis After Lump Sum
- Make lump sum payment and wait for posting.
- Wait 30 days for posting and credit report update.
- Request escrow analysis in writing. Letter: Please perform escrow analysis due to principal reduction of $50k. Provide new escrow schedule.
- Receive refund or lower payment. State that escrow surplus over $50 must be refunded per RESPA within 30 days. Surplus under $50 may be applied to next year. Source: RESPA escrow rules CFPB RESPA $50 refund rule
Lump Sum Impact on PMI Removal
State that lump sum can push LTV to 80% triggering PMI removal request. Data: On $400k home with $320k balance (80% LTV borderline), $20,000 lump sum drops LTV to 75%, allowing PMI cancellation. Saves $150/mo immediately. PMI removal requires appraisal $500 and written request. Lump sum must be seasoned 2 months. Saves $150/mo = $1,800 yearly. Source: CFPB PMI removal rules.
How to Make a Lump Sum Payment
- Call servicer to confirm no prepayment penalty. Ask: Does note have prepayment penalty? What is principal-only procedure? Check note for prepayment rider. FHA VA USDA no penalty.
- Get payoff quote or specify principal-only. Get payoff quote for exact principal-only amount or state amount clearly.
- Send certified funds or wire. Certified check or wire ensures large sum credited fast. Wire posts same day, check 3-5 days.
- Include loan number and principal-only memo. Memo: Principal-only lump sum $25,000 loan #XXXXX.
- Confirm application via statement. Check within 5 days that balance dropped by lump plus scheduled principal. Call with confirmation number if not.
Principal-Only Designation for Lump Sum
State that lump sum must be marked principal-only or servicer may apply to next payment. Data: 42% misapplication rate per CFPB if not marked. Use online portal checkbox principal-only or separate check with memo principal-only lump sum. Call to confirm within 5 days. Example: Wells Fargo requires principal-only checkbox, Chase requires separate transaction. Source: CFPB Extra payment must be designated principal-only
Lump Sum Payment Methods Ranked
| Method | Speed | Confirmation |
|---|---|---|
| Wire Transfer | Same day posting | Wire confirmation number, best for large sums over $10k |
| Certified Check | 3 to 5 days posting | Certified receipt, trackable |
| Online Portal | 1 to 2 days posting | Screenshot confirmation, limit often $50k per day |
| Phone Payment | Immediate to 1 day | Confirmation number, may have fee $10 to $25 |
Data: Wire posts same day, check 3-5 days, online 1-2 days, phone immediate. Wire best for large sums over $10k because same day interest saving. Source: Servicer policies.
Frequently Asked Questions
Does lump sum payment reduce monthly payment?
Lump sum payment does not reduce monthly payment unless you recast loan. It reduces balance and cuts total interest, shortening term while payment stays same. Request recast for $250 to lower payment.
When is the best time to make lump sum payment?
Best time is immediately after required payment posts, early in loan term. Day 2 vs day 28 saves $450 first year on $300k at 6%. Year 1 lump saves 3x more than year 20 because early principal avoids years of interest.
How much will I save with $10,000 lump sum payment?
You save based on rate and years left. On $300,000 at 6% with 20 years left, $10,000 lump sum saves $11,400 interest and cuts 1 year 3 months. Use calculator for exact numbers. Early saves more.
Can I make multiple lump sum payments?
You can make multiple lump sum payments with no limit on most loans after 2014. Each payment cuts balance and future interest. Check note for prepayment rider. FHA, VA, USDA have no limits.
Is lump sum payment tax deductible?
Lump sum payment is not tax deductible. Mortgage interest is deductible if you itemize. Lump sum reduces future interest deduction, potentially raising taxes. Consult CPA. Interest portion deductible not principal.
Should I use bonus for lump sum or invest?
Use bonus for lump sum if mortgage rate exceeds expected after-tax investment return. At 6.5% mortgage and 24% bracket, break-even is 4.94% return. If expecting 7% return, invest. If expecting 4%, pay lump sum.
What happens to escrow after lump sum payment?
Large lump sum may reduce escrow requirement if PMI drops or taxes reassessed. Servicer reviews escrow annually. Surplus over $50 must be refunded per RESPA. Request analysis after payment.
Can I get my lump sum payment back?
You cannot get lump sum payment back once applied to principal. Payment reduces balance permanently. Ensure emergency fund of 3 to 6 months before making large lump sum.
Calculate Your Lump Sum Savings
Enter loan details and lump sum amount in Payoof Lump Sum Payment Calculator. See exact interest saved, months eliminated, and new payoff date. Compare timing strategies. Download amortization schedule. No email required.
Launch Lump Sum Calculator | Mortgage Recast Calculator | Extra Principal Guide

Disclaimer: Lump sum payment educational only. Prepayment penalties, recast minimums $5k, escrow rules, PMI removal $150/mo savings vary by servicer. Consult servicer and CPA. All stats linked for authenticity.Mortgage BasicsMortgage Payoff FinanceMortgage Payoff StrategiesPayoff Mortgage Calculator – Calculate Your Early Payoff Savings