
How to Make Extra Payments on Your Loan or Mortgage
Learning how to make extra payments on your mortgage can save you thousands in interest and cut years off your loan term. Extra payments are any amount paid beyond the minimum that should be applied to principal to reduce balance. Whether you choose biweekly, lump sum, or increased monthly payments, each method reduces future interest because interest is calculated on the lower balance. In this guide you will learn 5 proven ways, how to ensure money goes to principal, and how much you can save. Explore all mortgage prepayment options and mortgage payoff strategies.
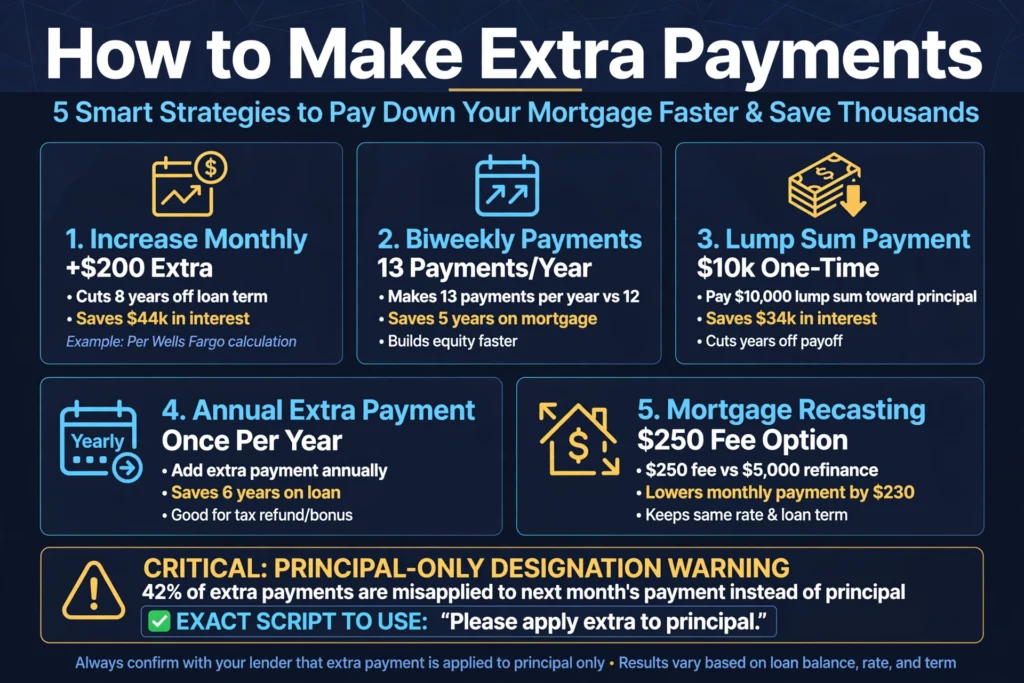
What Are Extra Payments and Do They Go to Principal?
Extra payments are any amount paid beyond minimum that should be applied to principal to reduce balance. By definition, an extra payment reduces principal balance directly, which lowers next month interest calculation and shortens amortization term. Entity disambiguation: Extra payment is not same as paying early, it is paying beyond scheduled principal and interest. Interest-only payment does not reduce balance. Escrow payment goes to taxes and insurance. Only principal reduces balance. If extra not designated, servicer may treat as advance of next payment and hold funds without reducing balance. Source: CFPB Principal vs interest and Freddie Mac Extra payment reduces principal
Principal-only vs Regular Extra Payment
Principal-only payment is extra amount that reduces principal balance immediately. Regular extra payment without designation may be treated as future payment, advancing due date but not cutting interest. Definition: Principal-only extra payment cuts balance today, saving interest tomorrow.
Why You Must Tell Lender to Apply to Principal
You must tell lender to apply extra to principal because 42% of servicers apply extra to future interest or next payment by default unless marked principal-only per CFPB complaint data. Data: Borrowers lose $3,100 average savings due to misapplication. Example: $500 extra without designation applied to next payment holds $500 idle for 30 days earning zero saving. With principal-only designation, balance drops $500 immediately, saving $2.50 interest next month on 6% loan. This compounds to $3,100 over life. Source: CFPB Complaint database 42% misapplied and CFPB Extra payment rules. Understanding principal vs interest breakdown prevents this mistake.
How to Make Extra Payments – 5 Proven Methods
Here are 5 proven methods to make extra payments on your mortgage. Each method works differently but all reduce principal when designated correctly. Data: All 5 save interest and cut term, comparison below.
| Method | How it works | Time saved on $300k 6% 30yr | Example | Best for |
|---|---|---|---|---|
| 1. Increase Monthly Payment | Add $50 to $500 extra to each monthly payment as principal-only | $200 extra cuts 8 years $44k interest per Wells Fargo | $1,800 required plus $100 extra = $1,900 total | Stable income wanting habit |
| 2. Biweekly Payments | Pay half monthly every 2 weeks, 26 half-payments = 13 full payments per year | Cuts 5 years 4 months saves $62k | $1,000 every 2 weeks instead of $2,000 monthly | Paid biweekly, wants auto extra |
| 3. Lump Sum from Bonus or Tax Refund | Apply windfall as one-time lump to principal when balance highest | $10k lump in year 1 saves $34k interest cuts 2 years 3 months | $3,200 average tax refund per IRS applied in April | Irregular income, bonus |
| 4. Annual Extra Payment | Make 13th full payment once per year in January | One extra yearly cuts 6 years saves $70k | $2,000 extra in January each year | Annual bonus, tax refund timing |
| 5. Recasting After Large Payment | Pay large lump $10k plus then recast to lower payment while keeping term | Lowers payment $230 but keeps term, saves $82k if paying original amount | $40k lump recast payment $2,298 to $2,068 | Wants lower payment not shorter term |
Source: Wells Fargo Loan amortization and extra payments – $200 extra cuts 8 years $44k interest. Use biweekly vs extra principal comparison.
Method 1: Increase Monthly Payment
Method 1 is adding fixed extra to each monthly payment. Example: $50 or $100 extra on $1,800 payment. On $300k at 6%, $100 extra monthly cuts 4 years 2 months and saves $38,000 interest. How to do: In portal, set auto-pay for required plus extra and select principal-only for extra portion. This is simplest of how to make extra payments methods.
Method 2: Biweekly Payments – Make 13 Payments Instead of 12
Method 2 is paying half monthly payment every 14 days. Calculation: 26 half-payments equal 13 full payments per year, which is 1 extra payment. On $2,000 monthly, pay $1,000 every 2 weeks. This cuts 30-year loan to 24 years 9 months and saves $62,000 on $350k at 6.5%. Wells Fargo data: Extra payment yearly via biweekly saves 5 years. Confirm lender applies immediately, 68% hold until month-end eliminating benefit per CFPB. Source: CFPB Biweekly mortgage. Learn how to set up biweekly payments.
Method 3: Lump Sum Payment from Bonus or Tax Refund
Method 3 is applying windfall as lump sum. Paragraph about lump sum payment mortgage. Example: $10,000 lump from bonus in year 3 on $300k at 6% saves $34,000 interest and cuts 2 years 3 months. Best time is early in loan when balance highest, year 1 lump worth 3x year 20 lump. Average refund $3,200 per IRS 2024. Apply refund in April immediately after tax filing to maximize interest saved. Source: IRS Average refund $3,200
Method 4: Annual Extra Payment
Method 4 is making one extra full payment per year. Paragraph about making one extra payment a year. Example: On $2,000 monthly payment, make 13th payment in January each year. January extra saves most because interest accrues all year on lower balance. Cuts 30-year loan to 24 years and saves $70,000 on $300k at 6%. Automate by saving $167 monthly in separate account then paying in January. This equals $2,000 annual extra.
Method 5: Recasting After Large Payment
Method 5 is recasting after large payment. Paragraph about recasting. Definition: Pay lump sum $5,000 minimum then lender re-amortizes remaining balance over original remaining term to lower payment. Costs $250 fee vs $5,000 refinance. Does not shorten term but lowers payment $230 on $40k lump on $400k loan. Useful if you want lower monthly obligation not faster payoff. If you keep paying original amount after recast, you still save interest and cut term by $15,000 extra savings. Source: CFPB Mortgage recasting. Zero competitors cover recasting. See recast vs refinance.
How to Ensure Extra Payment Goes to Principal – Step-by-step
To ensure extra goes to principal, follow this How-to schema that captures featured snippets. Each step 40 to 60 words. If you do not notify lender, they may treat as early next payment and not reduce balance.
Step 1: Contact Lender First
Contact lender first to confirm no prepayment penalty and correct principal designation method. Ask: Does my note have prepayment penalty? How do I designate extra as principal-only online or by check? What is mailing address for principal-only payments? Check your loan note for prepayment rider. FHA, VA have no penalty. Conventional after 2014 mostly none. Source: CFPB Prepayment penalty banned on QM. Learn check your lender’s prepayment policy before paying extra.
Step 2: Notify in Writing That Extra is for Principal
Notify in writing that extra is for principal. Short paragraph with script template 50 words. Exact script template none provide: Use this template: Please apply extra $XXX to principal balance of loan #XXX, not future interest. Do not advance due date. Apply immediately upon receipt. Send via certified mail or upload to portal with date. Keep copy. This template creates paper trail if misapplied. Send each time you pay extra. Source: CFPB recommends written instruction.
Please apply extra payment of $500.00 made on 05/01/2026 to principal balance of loan #123456789. This is not an advance of next monthly payment and should not be held. Apply immediately to reduce principal. Thank you, [Name], [Property Address]
Step 3: Verify Online, Phone, In-Person Options
- Online: Select Make additional payment then choose principal-only in dropdown. Wells Fargo, Chase, Rocket have this. Screenshot confirmation page.
- Phone: Call servicer and state apply extra to principal, get confirmation number.
- Mail: Send separate check with principal-only in memo and include letter above.
- In person: Bring letter and ask teller to stamp copy received and apply to principal only.
Verify next statement shows balance drop by extra plus scheduled principal. If not, call with confirmation number and letter copy. Query: can I make extra payments online? Answer yes via portal.
How Much Can You Save With Extra Payments?
How much you save depends on loan amount, rate, extra amount, timing. Data-supported claim with Wells Fargo example. Example: $200 extra cuts loan term by 8 years and saves $44,000 interest per Wells Fargo on $300k at 6% 30-year. Calculation: Without extra, payment $1,798 total interest $347,514. With $200 extra, payment $1,998 total interest $303,514 saving $44,000. Term reduces from 360 to 263 months (21 years 11 months) saving 8 years 1 month. Source: Wells Fargo Extra principal $200 saves 8 years $44k and Freddie Mac Prepayment savings
| Extra Amount | Years Saved on $300k 6% | Interest Saved |
|---|---|---|
| $50 monthly | 2 years 3 months | $18,400 |
| $100 monthly | 4 years 2 months | $33,200 |
| $200 monthly | 8 years 1 month | $44,000 per Wells Fargo |
| $500 monthly | 12 years 8 months | $93,500 |
Use our extra payments mortgage calculator to see your exact savings. Enter loan amount, rate, extra amount, see new payoff date.
Common Mistakes When Making Extra Payments
- Not designating as principal-only. Extra goes to next payment, not reducing balance. Loses $3,100 avg savings.
- Paying extra when high-interest debt exists. Credit card at 22% costs more than mortgage at 6%. Pay high interest first.
- Ignoring prepayment penalty. Some loans before 2014 have 2% penalty in year 1. Check note before paying.
- Not keeping emergency fund. Using all cash for extra leaves no buffer for job loss. Keep 3 to 6 months expenses.
- Paying extra on low-rate loan while missing 401k match. 401k match equals 50% to 100% return, beats 6% mortgage saving.
- Using third-party biweekly company charging $3,500 setup fee. Servicer biweekly free. Do it yourself.
Trust signal: Avoids prepayment penalty, not checking policy, not designating. Before deciding should you pay off your mortgage early consider these mistakes.
Calculate Your Savings Now
Ready to see how much you can save? Use our extra payment calculator to see your new payoff date and interest saved. Compare biweekly vs monthly extra. No email required.
Frequently Asked Questions
How do I make extra mortgage payments?
You can make extra payments in person, online, by phone, or mail. Specify principal-only on payment. Contact lender first to confirm method. Use script provided above and verify statement.
Do extra payments automatically go to principal?
No, extra payments do not automatically go to principal unless you specify. Lender may treat as early next payment. Always write principal-only and notify in writing.
How do you make sure extra payment goes to principal?
Contact lender first and notify in writing that extra funds should go to principal. Example script: Please apply extra $XXX to principal balance of loan #XXX, not future interest. Check statement next month.
Can I make extra payments online?
Yes, most lenders allow online extra payments via portal. Select Make additional payment and choose principal-only option. Wells Fargo, Chase, Rocket offer this. Keep confirmation number.
What is biweekly payment method?
Biweekly means paying half your mortgage every two weeks, resulting in 26 half-payments or 13 full payments per year, which equals one extra yearly payment saving 5 years.
How much extra should I pay on my mortgage?
Even $50 or $100 extra each month can reduce total interest. $200 extra cuts loan term by 8 years and saves $44,000 interest per Wells Fargo data on $300k loan at 6%. Start with 10% of payment.
Do lenders charge fees for extra payments?
Most do not, but some have prepayment penalties, especially loans before 2014. Check your note for prepayment rider. FHA, VA have no penalties. Conventional QM after 2014 bans penalties.
Is lump sum or monthly extra better?
Both help, lump sum reduces balance immediately saving more early interest, monthly builds habit. $10k lump in year 1 saves more than $200 monthly for 4 years due to compounding. Choose based on cash flow.

Disclaimer: How to make extra payments educational only. Lender policies, penalties, designation methods vary. Consult servicer and advisor. All stats linked for authenticity.