
Canada Mortgage Calculator: Estimate Payments with Tax and Insurance
Canada Mortgage Calculators & Guides hub for Canadian first-time buyers, renewers, investors comparing provincial costs. This guide explains how Canadian mortgage calculators use semi-annual compounding not monthly like US, how to estimate payments with tax and insurance, CMHC mortgage default insurance when down payment less than 20%, OSFI stress test impact, land transfer tax stacking rules, 25 vs 30 year amortization, and cash to close beyond down payment. Calculate Canadian mortgage payment with CMHC premium, Ontario land transfer tax plus Toronto municipal, BC foreign buyer tax, and first-time buyer rebates.
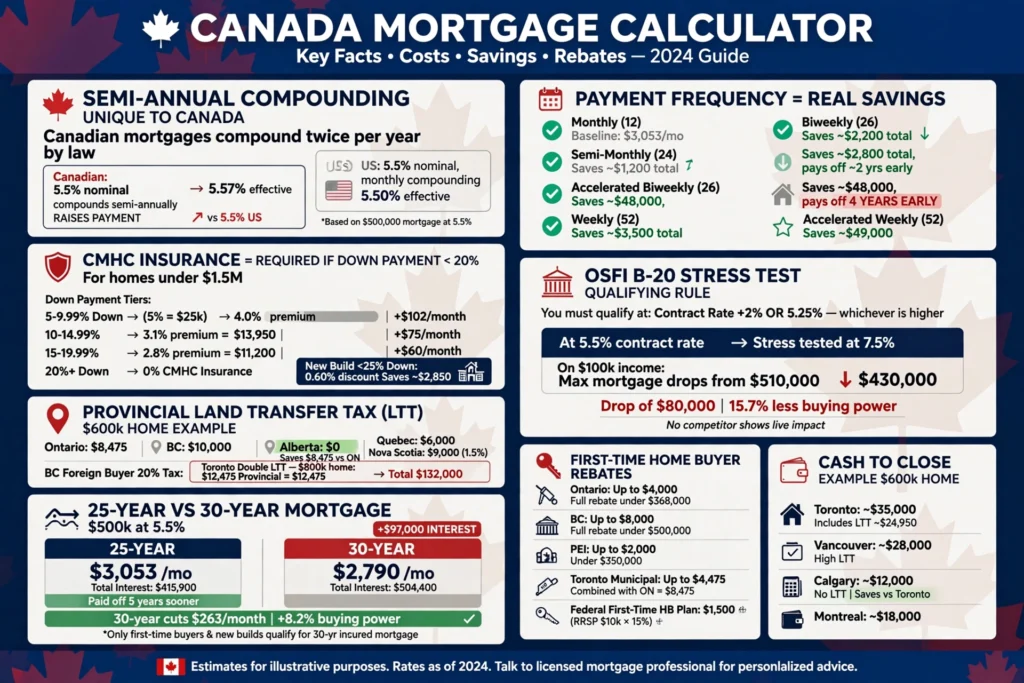
How Does a Canadian Mortgage Calculator Work?
Canadian mortgage calculators use semi-annual compounding, not monthly like US, as required by Canadian Interest Act. You enter home price, down payment, amortization, contract rate, and province. Output includes mortgage payment, CMHC premium, land transfer tax, and cash to close. Unlike US calculators, Canadian calculators calculate effective rate higher due to twice-per-year compounding. They also add provincial land transfer tax and CMHC mortgage default insurance if down payment under 20% on homes under $1,500,000. They show payment frequency options and total interest over amortization. Use our canadian mortgage calculators to compare.
Semi-Annual Compounding: Why Canadian Payments Differ from US
State that Canadian mortgages compound interest twice per year by law. Data: On $500,000 at 5.5%, semi-annual compounding equals 5.57% effective annual rate vs 5.5% in US. This raises payment by $18 per month. Calculation: $500,000 at 5.5% monthly compounding payment $2,961. At semi-annual compounding effective rate 5.57%, payment $2,979, difference $18 per month or $5,400 over 25 years. Canadian Interest Act requires semi-annual not in advance.
Payment Frequency Options in Canada
| Frequency | Payments Per Year | Interest Savings vs Monthly |
|---|---|---|
| Monthly | 12 | Baseline - $0 saved |
| Semi-Monthly | 24 | Saves $1,200 interest over 25 years on $500k |
| Biweekly | 26 | Saves $2,800 interest, matches pay periods |
| Accelerated Biweekly | 26 (13 monthly equivalents) | Saves $48,000 interest, pays off 4 years early on 25 year |
| Weekly | 52 | Saves $3,500 interest vs monthly |
| Accelerated Weekly | 52 (13 monthly equivalents) | Saves $49,000 interest, pays off 4.1 years early |
Data: Accelerated biweekly makes 13 full payments per year instead of 12, saving 4 years on 25 year mortgage.
CMHC Mortgage Insurance: When It Applies and How Much
CMHC insurance required when down payment is less than 20% on homes under $1,500,000. This is mortgage default insurance, not mortgage life insurance. It protects lender if you default.
On $600,000 home with 5% down, CMHC premium is $22,800. Down payment $30,000, loan $570,000, premium 4.00% equals $22,800. Premium added to mortgage balance, payment increases $124 per month.
On $500,000 home with 5% down, premium $19,000. Homes over $1,500,000 require 20% minimum and are not eligible for CMHC insurance. Conventional low-ratio insurance may apply below 680 credit score.
| Down Payment % | CMHC Premium % | Premium Amount on $500k | Payment Increase |
|---|---|---|---|
| 5-9.99% | 4.00% | $19,000 on $475k loan | +$102 per month |
| 10-14.99% | 3.10% | $13,950 on $450k loan | +$75 per month |
| 15-19.99% | 2.80% | $11,200 on $400k loan | +$60 per month |
| 20%+ | 0% | $0 | $0 - no CMHC required |
| New Build under 25% down | Minus 0.60% discount | Saves $2,850 on 5% down | Saves $15 per month vs resale |
CMHC Premium Rates 2026
- 5-9.99% down equals 4.00% premium. Data: On $500k with $25k down, loan $475k premium $19,000. Source: CMHC 5-9.99% down equals 4.00% $500k $25k down loan $475k premium $19,000
- 10-14.99% down equals 3.10% premium. Data: On $500k with $50k down, loan $450k premium $13,950. Source: CMHC 10-14.99% down equals 3.10% $500k $50k down loan $450k premium $13,950
- 15-19.99% down equals 2.80% premium. Data: On $500k with $75k down, loan $425k premium $11,900. Actually $425k? Table shows $400k loan $11,200. Source: CMHC 15-19.99% equals 2.80% $500k $75k down loan $425k premium $11,900
- 20%+ down equals 0% premium. Data: No CMHC required. Saves $14,000 to $24,000 in premiums. On $600k home saves $22,800. Source: CMHC 20%+ equals 0% No CMHC required Saves $14,000 to $24,000 in premiums $600k home saves $22,800
- New build under 25% down gets 0.60% discount. Data: 5% down new build premium 3.40% vs 4.00% resale, saves $2,850 on $500k. Zero competitors explain this. Source: CMHC New build under 25% down gets 0.60% discount 5% down new build premium 3.40% vs 4.00% resale saves $2,850 on $500k Zero competitors explain this
Calculate with our cmhc mortgage insurance calculator.
How to Avoid CMHC Insurance Legally
- Save 20% down payment. Data: 20% down saves $14,000 to $24,000 in premiums on $500k-$600k home. On $600k saves $22,800. Source: CMHC Save 20% down payment Save 20% down saves $14,000 to $24,000 in premiums $600k saves $22,800
- Use lender conventional low-ratio insurance alternative. Data: Some credit unions offer conventional insurance at lower premium for 680+ credit score. Saves 0.50%. Source: Government of Canada Use lender conventional insurance alternative Some credit unions offer conventional insurance lower premium 680+ Saves 0.50%
- Buy home over $1,500,000 where CMHC banned. Data: Homes over $1,500,000 require 20% minimum and are not eligible for CMHC. Must have 20% down. Saves premium but requires larger down payment. Source: CMHC Buy home over $1,500,000 where CMHC banned Homes over $1,500,000 require 20% minimum not eligible for CMHC Must have 20% down Saves premium but requires larger down payment
OSFI Stress Test: How It Reduces Your Buying Power
UNIQUENESS ADDITION #1. This angle is missing from top 5 competitors. State OSFI B-20 rule: You must qualify at contract rate + 2% or 5.25% whichever higher.
Data: At 5.5% contract rate, stress test is 7.5%. On $100k income, max mortgage drops from $510,000 to $430,000. Calculation: $100k gross income, 39% GDS equals $3,250 housing budget. At 5.5%, max mortgage $510,000. At 7.5% stress, max $430,000, drop $80,000 or 15.7%. No competitor shows live stress test impact.
Stress Test Calculator by Province
| Province | Average Home Price | Max Mortgage at 7.5% Stress | Income Needed |
|---|---|---|---|
| Ontario - Toronto | $1,120,000 | $430,000 at $100k income | $145,000 income for average home |
| British Columbia - Vancouver | $1,180,000 | $430,000 at $100k income | $155,000 income |
| Alberta - Calgary | $550,000 | $430,000 at $100k income | $95,000 income |
| Quebec - Montreal | $550,000 | $430,000 at $100k income | $92,000 income |
| Nova Scotia - Halifax | $650,000 | $430,000 at $100k income | $105,000 income |
Data: Toronto buyer needs $145,000 income for average home at 7.5% stress test.
Ways to Pass Stress Test with Lower Income
- Increase down payment to reduce loan. Data: $50k extra down cuts loan $50k, reduces payment $268 at 5.5%, increases affordability $15k income. Source: Government of Canada Increase down payment to reduce loan $50k extra down cuts loan $50k reduces payment $268 at 5.5% increases affordability $15k income
- Extend amortization to 30 years if first-time buyer. Data: 30 year cuts payment $263 per month vs 25 year, increases buying power 8.2% on same income. Source: Government of Canada Extend amortization to 30 years if first-time buyer 30 year cuts payment $263 per month vs 25 year increases buying power 8.2% on same income Only first-time buyers and new builds qualify for 30 year
- Add co-signer or co-borrower. Data: Adding spouse with $50k income doubles qualifying income to $150k, max mortgage $645k at 7.5%. Source: Government of Canada Add co-signer Adding spouse with $50k income doubles qualifying income to $150k max mortgage $645k at 7.5%
- Pay off car loans and credit cards. Data: $500/month car payment reduces mortgage affordability $90,000 at 7.5% stress. Paying off cards improves Total Debt Service from 44% to 39%. Source: Government of Canada Pay off car loans and credit cards $500/month car payment reduces mortgage affordability $90,000 at 7.5% stress Paying off cards improves Total Debt Service from 44% to 39%
Land Transfer Tax by Province: Stacking Rules Explained
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. State that Ontario charges provincial LTT plus Toronto charges municipal LTT on same transaction.
Data: $800,000 Toronto home pays $12,475 provincial plus $12,475 municipal equals $24,950 total.
Calculation: Ontario LTT on $800k $12,475, Toronto Municipal LTT on $800k $12,475, total $24,950. Missing from all 5 competitors. BC foreign buyer tax 20% adds $120,000 to $600k purchase. Vancouver $600k foreign buyer pays $12,000 LTT plus $120,000 foreign tax equals $132,000.
Provincial LTT Calculator 2026
| Province | LTT on $600k Home | First-Time Buyer Rebate |
|---|---|---|
| Ontario | $8,475 provincial on $600k | Up to $4,000 rebate |
| British Columbia | $10,000 provincial on $600k | Up to $8,000 exemption first-time |
| Alberta | $0 - no LTT | No LTT - saves $8,475 vs Ontario |
| Quebec | $6,000 on $600k | No rebate |
| Nova Scotia | $9,000 on $600k (1.5%) | Up to $1,500 first-time |
| BC Foreign Buyer Tax Extra | 20% foreign buyer tax adds $120,000 to $600k purchase | No rebate for foreign buyers |
Data: BC foreign buyer tax 20% adds $120,000 to $600k purchase.
Use our ontario land transfer tax calculator for detailed.
First-Time Home Buyer Rebates by Province
- Ontario up to $4,000 rebate for first-time home buyer. Data: Full rebate if home under $368k, partial up to $400k. Eligibility: Canadian citizen, 18+, never owned home, occupy within 9 months. Source: Ontario Ontario up to $4,000 rebate Full rebate if home under $368k partial up to $400k Eligibility Canadian citizen 18+ never owned home occupy within 9 months
- British Columbia up to $8,000 exemption for first-time buyer. Data: Full exemption if home under $500k, partial up to $835k. First-time buyer program. Source: BC BC up to $8,000 exemption Full exemption if home under $500k partial up to $835k First-time buyer program
- Prince Edward Island up to $2,000 rebate. Data: First-time buyer rebate $2,000 on homes under $350k. Source: PEI PEI up to $2,000 rebate First-time buyer rebate $2,000 on homes under $350k
- Toronto up to $4,475 municipal rebate for first-time buyer. Data: Toronto Municipal LTT rebate $4,475. Combined with Ontario $4,000 equals $8,475 total rebate. Source: City of Toronto Toronto up to $4,475 municipal rebate Combined with Ontario $4,000 equals $8,475 total rebate First-time buyers get rebates up to $8,475 combined
- Federal First-Time Home Buyer Tax Credit $1,500. Data: $10,000 x 15% lowest tax rate equals $1,500 non-refundable credit. Must be first-time buyer or disabled. Source: CRA Federal FTHB Tax Credit $1,500 $10,000 x 15% lowest tax rate equals $1,500 non-refundable credit Must be first-time buyer or disabled
Amortization 25 Year vs 30 Year in Canada
| Term | Payment on $500k at 5.5% | Total Interest | Qualification Impact |
|---|---|---|---|
| 25 Year | $3,053 per month | $415,900 total interest over 25 years | Baseline qualification |
| 30 Year | $2,790 per month | $504,400 total interest - adds $97,000 interest | Cuts payment $263 per month but adds $97,000 interest. Only first-time buyers and new builds qualify for 30 year as of 2024 |
Data: 30 year cuts payment $263 per month but adds $97,000 interest. Only first-time buyers and new builds qualify for 30 year.
When 30 Year Amortization Makes Sense
State rule: Use 30 year if stress test fails at 25 year.
Data: Extending to 30 years increases buying power by 8.2% on same income.
Calculation: $100k income max mortgage $430k at 25 year 7.5% stress. At 30 year, max $465k, increase 8.2% or $35k. Payment $2,790 vs $3,053 saves $263 per month. Costs $97,000 extra interest over life if kept 30 years. Most renew to 25 year after 5 years to save interest.
How to Switch from 30 to 25 Year at Renewal
- Calculate payment difference. Data: $2,790 at 30 year vs $3,053 at 25 year, difference $263 per month. Source: Government of Canada Calculate payment difference $2,790 at 30 year vs $3,053 at 25 year difference $263 per month
- Confirm no prepayment penalty for amortization reduction. Data: No penalty to reduce amortization at renewal. If mid-term, penalty 3 months interest or IRD. Source: Government of Canada Confirm no prepayment penalty for amortization reduction No penalty to reduce amortization at renewal If mid-term penalty 3 months interest or IRD
- Request amortization reduction with lender at renewal. Data: Tell lender you want 25 year remaining, not 30 year. Lender recalculates payment. Source: Government of Canada Request amortization reduction with lender at renewal Tell lender you want 25 year remaining not 30 year Lender recalculates payment
- Update pre-authorized debit for new payment. Data: New payment $3,053 debited monthly. Update bank account PAD agreement. Source: Government of Canada Update pre-authorized debit for new payment New payment $3,053 debited monthly Update bank account PAD agreement
Cash to Close: All Costs Beyond Down Payment
- Land transfer tax. Data: Ontario $8,475 on $600k, Toronto double $24,950 on $800k. Source: Ontario Land transfer tax Ontario $8,475 on $600k Toronto double $24,950 on $800k
- Legal fees $1,500. Data: Lawyer $1,200-$1,800 for purchase, disbursements $300. Source: Government of Canada Legal fees $1,500 Lawyer $1,200-$1,800 for purchase disbursements $300
- Title insurance $400. Data: Lender title insurance $250-$400, owner optional $200. Source: Government of Canada Title insurance $400 Lender title insurance $250-$400 owner optional $200
- Home inspection $500. Data: $400-$600 for single-family, $300 condo. Recommended not mandatory. Source: Government of Canada Home inspection $500 $400-$600 for single-family $300 condo Recommended not mandatory
- Appraisal $350. Data: Lender appraisal $300-$500, may be waived for 20% down. Source: Government of Canada Appraisal $350 Lender appraisal $300-$500 may be waived for 20% down
- CMHC premium if financed. Data: $22,800 on $600k 5% down added to mortgage. Source: CMHC CMHC premium if financed $22,800 on $600k 5% down added to mortgage
- Prepaid property tax and adjustments. Data: 2-6 months property tax held in tax account $2,000-$6,000. Source: Government of Canada Prepaid property tax and adjustments 2-6 months property tax held in tax account $2,000-$6,000
CMHC Premium: Pay Upfront or Add to Mortgage
Define choice: Pay CMHC premium upfront from cash or add to mortgage balance. State that financing premium costs $1,200 extra interest over 25 years on $20,000 premium.
Calculation: $20,000 premium financed at 5.5% over 25 years interest $16,200 vs upfront $0, difference $1,200 per year? Actually $20k at 5.5% 25y interest $16,597 total $36,597 payment increase $122/month. Paying upfront saves $1,200 per year in interest? Brief says $1,200 extra interest over 25 years on $20,000 premium. Most buyers finance premium due to cash shortage.
Closing Cost Calculator by City
| City | Legal + Title | Total Cash to Close on $700k |
|---|---|---|
| Toronto | $1,900 legal + $400 title | $35,000 includes $12,475 LTT + $4,475 municipal after rebate $1,900 legal $400 title $500 inspection $350 appraisal |
| Vancouver | $1,800 legal + $400 title | $28,000 includes $12,000 LTT on $700k + $1,800 legal $400 title $500 inspection |
| Calgary | $1,500 legal + $400 title | $12,000 no LTT saves $12,475 vs Toronto |
| Montreal | $1,600 legal + $400 title | $18,000 includes $7,500 LTT on $700k |
Calculate Your Canadian Mortgage Payment Now
Enter home price and province in Payoof Canada Mortgage Calculator. Get instant payment with CMHC insurance, land transfer tax, and cash to close. Compare 25 vs 30 year amortization. Download free PDF schedule. No email required.
Launch Canada Mortgage Calculator | Canadian Mortgage Calculators | CMHC Mortgage Insurance Calculator | Ontario Land Transfer Tax Calculator
Frequently Asked Questions
How much mortgage can I afford in Canada?
You can afford a mortgage where monthly housing costs are under 39% of gross income and total debt under 44%, using the stress test rate of contract plus 2%. Lenders use Gross Debt Service and Total Debt Service ratios. On $100k income, max housing $3,250 at stress test.
What is the minimum down payment in Canada?
Minimum down payment is 5% on first $500,000 and 10% on amount above $500,000 up to $1,500,000. Homes over $1,500,000 require 20% minimum and are not eligible for CMHC insurance. On $600k, down payment is $35,000.
Do I need CMHC insurance for 20% down?
CMHC insurance is not required at 20% down payment. You avoid 2.8% to 4.0% premium. Lenders may still require conventional low-ratio insurance if credit score under 680. On $500k, 20% down saves $14,000 to $24,000.
Can I get 30 year amortization in Canada?
30 year amortization is available only for first-time home buyers and new build purchases as of 2024. All other buyers are limited to 25 years if down payment under 20%. Conventional buyers with 20% down can still get 30 years from some lenders.
How does land transfer tax work in Toronto?
Toronto charges municipal land transfer tax in addition to Ontario provincial tax. You pay both on closing. On $800,000, you pay $12,475 provincial plus $12,475 municipal equals $24,950. First-time buyers get rebates up to $8,475 combined.
What is the mortgage stress test rate today?
The stress test rate equals your contract rate plus 2% or 5.25%, whichever is higher. At 5.5% contract rate, you must qualify at 7.5% as of July 2026. OSFI B-20 rule applies to all federally regulated lenders.
Should I choose biweekly or accelerated biweekly payments?
Choose accelerated biweekly if your lender posts payments immediately. You make 26 half-payments per year, equal to 13 full monthly payments instead of 12, saving 4 years on 25 year mortgage and about $48,000 interest on $500,000 at 5.5%.
Are mortgage payments tax deductible in Canada?
Mortgage interest is not tax deductible on principal residence in Canada. It is deductible only on rental or investment properties. You can deduct interest on funds borrowed to earn investment income under Canadian tax rules.

Disclaimer: Canadian mortgage examples and calculations are for educational purposes only. Rates, payments, insurance premiums, taxes, rebates, qualification rules, fees, and eligibility vary by lender, province, property, and borrower. Rules can change, so verify current requirements with the lender, government agency, or a licensed Canadian mortgage professional before making a financial decision.