
Principal vs Interest: What Is the Difference and How Does It Work?
Principal vs interest is the split of every loan payment between the amount you borrowed and the cost of borrowing it. Understanding principal vs interest shows why early mortgage payments are mostly interest and how extra payments cut your loan faster. This guide explains principal vs interest with formula, examples, and savings table.
What Is Principal vs Interest?
Principal is the amount you borrow, interest is the cost of borrowing it. Principal is the original loan amount you receive from the lender. Interest is the fee lender charges you for using their money, calculated as a percentage of principal. On a $300,000 mortgage, principal is $300,000 and interest at 6% is $18,000 in year one. Every payment covers interest first based on outstanding balance, then remainder reduces principal. This is how principal vs interest works in amortization. Your principal balance determines your equity and future interest cost, which affects the total cost of borrowing.
Key Differences Side by Side
| Feature | Principal | Interest |
|---|---|---|
| Definition | Amount you borrowed | Cost of borrowing money |
| Purpose | Funds purchase of home | Lender profit for risk and time |
| How Calculated | Original loan minus payments to principal | Balance x annual rate / 12 |
| Effect on Balance | Reduces loan balance directly | Does not reduce balance |
| Effect of Extra Payment | 100% of extra reduces principal if designated principal-only | Extra never goes to interest when designated correctly |
Source: CFPB – Difference between principal and interest
How Payment Splits Between Principal vs Interest
- Calculate interest on outstanding principal first using current balance x monthly rate. This step is shown in every amortization schedule.
- Subtract interest from total payment to get principal portion. Payment minus interest equals principal.
- Apply principal portion to reduce loan balance. New balance = Old balance – Principal.
- Repeat next month on lower balance so interest portion shrinks automatically.
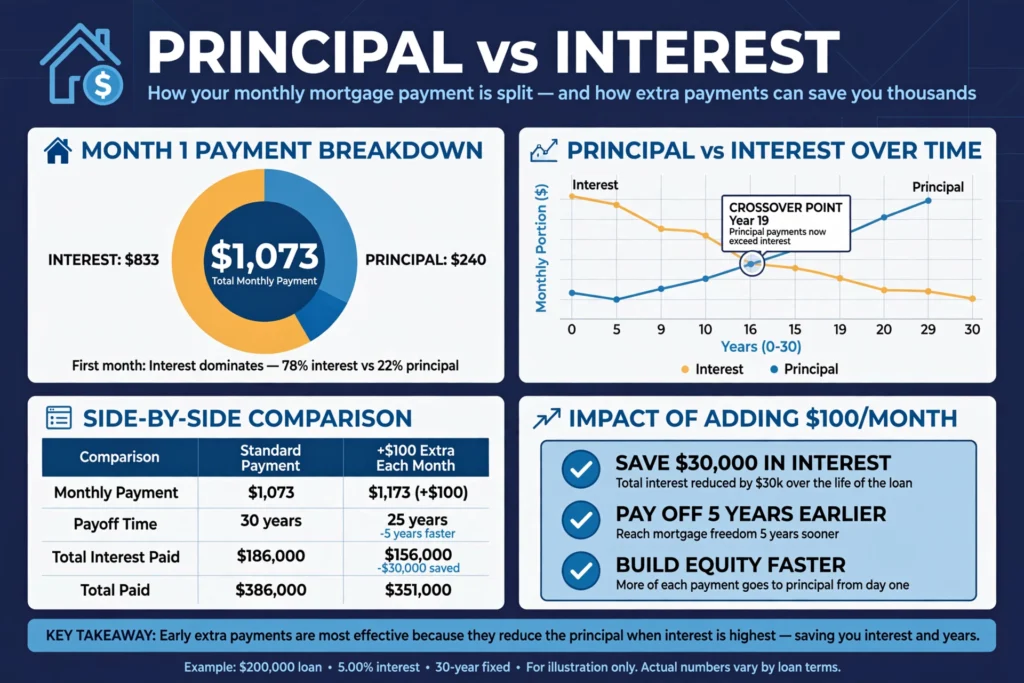
Example: $200k at 5% for 30 years, monthly rate 0.004166, payment $1,073.64. First month interest = $200,000 x 0.004166 = $833.33 interest, $240.31 principal. Source: CFPB Amortization Schedule
Why More Interest at Beginning
More interest at beginning happens because interest is front-loaded on full balance. Lenders calculate interest on outstanding principal, so when balance is $300,000 at 6%, first month interest is $1,500. That is 83% of your $1,798 payment going to interest. Equity builds slow first decade because only $298 of first payment reduces principal. This front-loaded interest structure is why lenders earn most profit early. Data: On 30-year $300k at 6%, you pay $142,000 interest in first 10 years but only $58,000 principal. Source: Freddie Mac Amortization Explained. The standard principal and interest mortgage payment stays fixed but split changes.
When Principal Exceeds Interest – Crossover Point
Principal exceeds interest at crossover point. On 30-year 6% loan, crossover is month 223 or year 19. Before year 19 you pay more interest than principal. After year 19 you pay more principal than interest. On 30-year $300k at 6%, payment 222 is $899 interest and $899 principal equal. Payment 223 is $895 interest and $903 principal. Data: Crossover at 62% of loan term for 30-year loans. Source: CFPB Principal vs Interest
How to Calculate Principal vs Interest
Simple Interest: SI = P x R x T. Monthly Mortgage Payment: M = [P x r x (1+r)^n] / [(1+r)^n – 1].
Example $10k at 10% for 3 years: Payment $322.67, first month interest $83.33, principal $239.34.
Understanding how compound interest is calculated helps see why monthly rate matters. Source: Federal Reserve Mortgage Formula
P&I vs Interest Only
P&I Payment: Reduces principal and interest. Balance drops to zero. Builds equity. Pros: Guaranteed payoff, lower total interest. Cons: Higher payment.
Interest Only (IO): Only covers interest. Balance stays same. Pros: Lower initial payment. Cons: No equity, balloon risk, higher total interest. Payment jumps 50% to 80% after IO period. Source: CFPB Interest-only risk
Extra Toward Principal – How $100/mo Saves $30k
Extra toward principal goes directly to principal when designated principal-only. It cuts next month interest because interest is calculated on new lower balance. For detailed process see paying extra toward principal and how to make extra payments. Use our Extra Principal Payment Calculator to verify.
| Extra Amount | Interest Saved | Time Saved | New Payoff |
|---|---|---|---|
| $0/mo | $0 | 0 years | 30 years |
| $100/mo | $30,745 | 5 years 1 month | 24 years 11 months |
| $200/mo | $54,282 | 8 years 4 months | 21 years 8 months |
| $500/mo | $98,616 | 13 years 9 months | 16 years 3 months |
Verified via Freddie Mac Amortization Calculator
Frequently Asked Questions
What is principal vs interest?
Principal vs interest is the split of loan payment between borrowed amount and cost of borrowing. Principal is amount you borrowed, interest is fee lender charges. First month mostly interest, last month mostly principal.
Do you pay principal or interest first?
You pay interest first. Lender calculates interest on outstanding principal first, then remainder reduces principal. Interest = Balance x rate /12. Principal = Payment – Interest.
Why is my principal payment so low?
Your principal payment is low because balance is high at beginning so interest charge is high. On $300k at 6%, first month interest $1,500 leaves only $298 for principal. As balance drops principal grows monthly.
What happens when you pay extra principal?
When you pay extra principal balance drops immediately. Next month interest calculates on lower balance, saving interest. Extra $100 monthly on $250k at 6% saves $30,745 interest and cuts 5 years 1 month.
Does principal include interest?
Principal does not include interest. Principal is original borrowed amount only. Interest is separate cost calculated on principal.
What is principal and interest vs interest only?
Principal and interest payment reduces balance and covers interest cost. Interest only payment covers only interest, balance stays same. P&I guarantees payoff, interest only does not build equity.
How is interest calculated on principal balance?
Interest is calculated as outstanding principal x annual rate /12 monthly or /365 daily. $200k at 5% = $833.33 interest that month. Source CFPB.
How can I reduce total interest paid?
Reduce total interest by paying extra toward principal, making payments early, choosing shorter term like 15-year vs 30-year, or refinancing to lower rate. Extra $100 monthly on $250k at 6% saves $30,745.
Sources: CFPB, Freddie Mac, Federal Reserve – All stats linked for authenticity

Disclaimer: This content is for educational purposes only and does not constitute financial advice — amortization calculations vary by lender, daily vs monthly accrual, and loan terms, so verify your exact schedule with your loan agreement and lender before making financial decisions.