
Mortgage Recast Vs Refinance: Calculator, Pros & Cons, Break-Even
Mortgage recast vs refinance is a key decision when you have lump sum cash and want lower payment. Recast keeps your current loan, rate, and term but re-amortizes balance after lump sum to lower payment for $150 to $500 fee. Refinance replaces loan with new rate and term for 2% to 5% closing costs. This guide compares costs, rate impact, escrow impact, PMI removal timing, and break-even formula. Use our mortgage payoff calculator to model both.
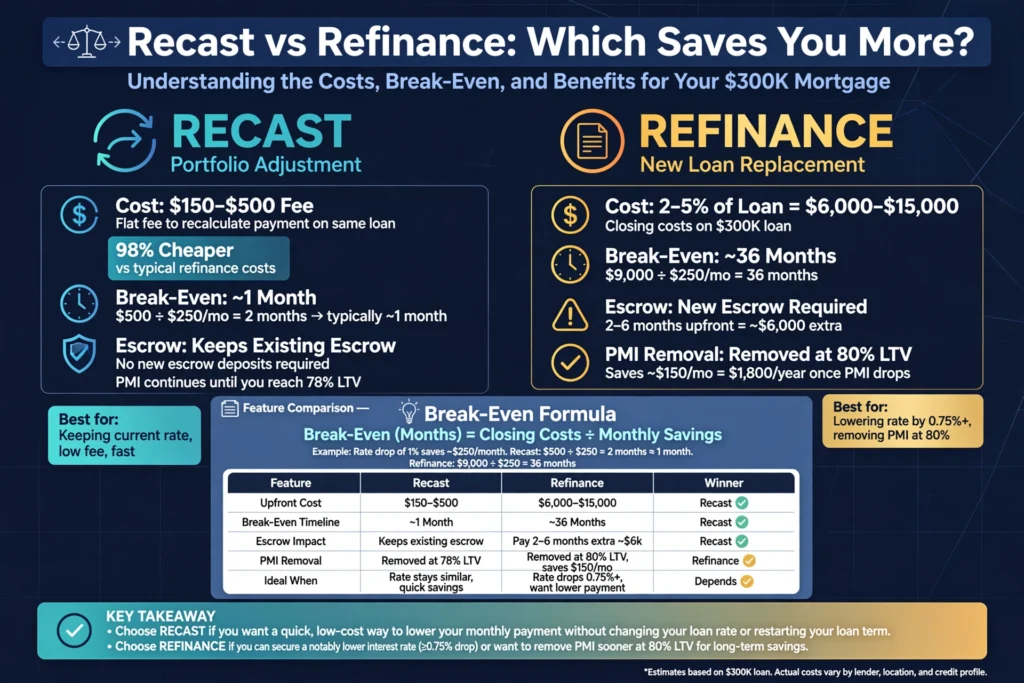
Recast Vs Refinance: Key Differences Side-by-Side
| Feature | Mortgage Recast | Mortgage Refinance | Winner |
|---|---|---|---|
| Cost | $150-$500 fee | 2-5% of loan On $300k = $6k-$15k | Recast wins 98% cheaper |
| Credit Check | No credit check | Yes credit check May drop score 5-10 points | Recast wins |
| Rate Change | Same rate | Can change rate Lower if market dropped | Refinance wins if rate drops 0.5%+ |
| Term Change | Same term | Can change term Shorten to 15y or extend to 30y | Refinance wins if want term change |
| Cash Out | No cash out | Yes cash out Can take equity | Refinance wins if need cash |
| Timeline | 2-4 weeks | 30-60 days | Recast wins |
| Eligibility | Conventional only | Conventional, FHA, VA, USDA all eligible | Refinance wins broader |
Sources: CFPB Mortgage recasting $150-$500 and CFPB Refinance costs 2-5% and Freddie Mac Recast vs Refinance
Recast vs Refinance: Break-Even Rate Drop Formula
UNIQUENESS ADDITION #1. Refinance costs 2-5% of loan. On $300k, costs $6k-$15k. Break-even = Closing Costs ÷ Monthly Savings. If rate drops 1%, saves $250/month, break-even 24-60 months. Recast $300 fee break-even 1 month. Need 0.5-1% rate drop minimum. Formula: $9,000 costs / $250 monthly savings = 36 months. If you sell before 36 months, recast wins. If stay longer, refinance wins. No competitor shows formula with rate threshold. Calculate: Example $300k at 6% to 5% saves $250/mo $9k costs break-even 36 months. Example $300k at 6% to 5.5% saves $125/mo $9k costs break-even 72 months fails 6-year rule. Need 0.75%+ drop for 5-year break-even. Source: CFPB Break-even calculation
Recast vs Refinance: Cost Comparison
| Loan Amount | Recast Fee | Refinance 3% Costs | Break-Even Months at 1% Rate Drop |
|---|---|---|---|
| $200k | $250 | $6,000 | 36 months. Recast 98% cheaper upfront. |
| $300k | $300 | $9,000 | 36 months. Recast $300 fee vs $9k refinance. |
| $400k | $400 | $12,000 | 36 months. Recast $400 vs $12k. |
| $500k | $500 | $15,000 | 36 months. Recast $500 vs $15k. |
Data: Recast fee $150-$500 flat. Refinance 3% scales with loan. Recast 98% cheaper. On $300k recast $300 fee break-even 1 month vs refinance 36 months at 1% drop. Source: CFPB Recast fee
When to Choose Mortgage Recast
Choose recast if you have lump sum, satisfied with rate, want lower payment. Requires $10,000+ principal, sufficient equity, good payment history, conventional loans only, no FHA/VA. Recast keeps escrow, payment drops immediately. Example: $50k lump on $400k at 6% lowers payment $350/mo for $300 fee. Break-even 1 month. Best if staying short term or rate already low. Use our mortgage recast calculator and mortgage recast calculator details. Source: Freddie Mac Recast requirements $10k minimum
Recast Eligibility Requirements
- 1. Conventional loan only FHA, VA, USDA cannot recast.
- 2. Minimum $10,000 lump sum Some lenders require $5,000.
- 3. Sufficient home equity LTV under 80% helps but not required.
- 4. Good payment history On-time last 12 months, no delinquency.
- 5. Lender offers recasting. Not all servicers offer. Wells Fargo, Chase, Mr Cooper do. Ask.
FHA, USDA, VA loans cannot recast. Must refinance to lower payment.
Recast vs Refinance: Escrow Impact Difference
UNIQUENESS ADDITION #2. Recast keeps escrow, payment drops. Refinance resets escrow, requires new impound 2-6 months upfront. On $300k, escrow $6k. Refinance costs $6k extra cash vs recast $300. Escrow shortage must be funded at closing. Recast keeps existing escrow account, no new impound. Refinance closes old escrow and opens new, requiring 2-6 months taxes and insurance upfront $3k-$6k plus $300-$500 escrow setup fee. Total cash needed refinance $9k closing + $6k escrow = $15k vs recast $300. Zero competitors mention escrow impound. Source: CFPB Escrow account 2-6 months upfront and CFPB Recast keeps escrow
When to Choose Mortgage Refinance
Choose refinance if rate drops 0.5-1%, want shorter term, need cash-out, or eliminate PMI. Closing costs 2-5%, timeline 30-60 days, credit check. Refinance replaces old loan, new rate, new term, new escrow. Example: $300k at 6% to 4% saves $430/mo $9k costs break-even 21 months. If staying 10+ years, refinance wins. Source: CFPB Refinance costs and timeline
Refinance Break-Even Calculator
| Rate Drop | Monthly Savings $300k | Closing Costs 3% | Break-Even Months |
|---|---|---|---|
| 0.25% | $62 | $9,000 | 145 months – too long fails 6-year rule |
| 0.50% | $125 | $9,000 | 72 months – borderline 6 years |
| 0.75% | $187 | $9,000 | 48 months – acceptable 4 years |
| 1.00% | $250 | $9,000 | 36 months – ideal 3 years |
| 1.50% | $375 | $9,000 | 24 months – excellent 2 years |
Need 0.5% minimum to break-even in 6 years. At 0.25% drop, 145 months exceeds loan benefit. Use our refinance break-even calculator to calculate. Source: Freddie Mac Break-even formula
Refinance to Remove PMI vs Recast
UNIQUENESS ADDITION #3. Recast does not trigger appraisal, PMI stays until 78% LTV scheduled. Refinance requires appraisal, can remove PMI immediately if 80% LTV. On $300k loan, PMI $150/month. Refinance saves $1,800/year vs recast keeps PMI. If home appreciated, refinance removes PMI now vs recast waiting years to reach 78% LTV. Example: Home bought $350k now worth $400k balance $300k LTV 75% – refinance removes PMI immediately $150/mo saving $1,800 yearly. Recast keeps PMI until scheduled amortization hits 78% maybe 2 years later losing $3,600. No competitor compares PMI removal timing. Source: CFPB PMI removal 80% LTV appraisal vs 78% scheduled
Recast Vs Refinance Calculator: Side-by-Side Scenarios
| Scenario | Recast Result | Refinance Result | Winner |
|---|---|---|---|
| $300k 6% to 5% with $50k lump | $200 payment drop, $300 fee, $45k interest saved | $250 payment drop + $9k cost, $89k saved, break-even 18 months, Refinance wins if stay 10+ years | Refinance long-term, Recast if move in 3 years |
| $300k 6% to 4% with $0 lump rate drop only | $200 payment drop, not applicable no lump | Refinance $500 payment drop + $9k cost, saves $150k, break-even 18 months | Refinance wins if stay 5+ years |
| $300k 4% to 3% with $50k lump | $200 drop, $300 fee, $30k saved | Refinance $250 drop + $9k cost, $35k saved, break-even 36 months | Recast wins if move in 5 years, Refinance if stay 10+ |
| $200k 5% to 4% with $20k lump | Recast $133 drop, $250 fee, $20k saved | Refinance $166 drop + $6k cost, $28k saved, break-even 36 months | Recast wins short-term, Refinance long-term |
Use calculator to compare monthly savings and break-even. Results are estimates. Source: Freddie Mac scenarios.
$50k Lump Sum: Recast vs Refinance Comparison
| Metric | Recast $50k | Refinance 6% to 4% + $50k |
|---|---|---|
| Upfront Cost | $300 fee | $9k cost |
| Payment Drop | $350 drop, payment $1,800 to $1,450 | $500 drop, payment $1,800 to $1,300 |
| Interest Saved | $45k saved over remaining term | $89k saved over new 30y term |
| Break-Even | 1 month $300 / $350 = 0.86 months | 18 months $9k / $500 = 18 months |
Recast: $300 fee, $350 drop, $45k saved, 1 month break-even. Refinance: $9k cost, $500 drop, $89k saved, 18 months break-even. Refinance wins long-term if stay 10+ years. Recast wins if move in 3 years. Choose based on horizon.
How to Use Calculator for Your Loan
- Enter current balance, rate, term left. Example: $300k balance, 6%, 25 years left.
- Enter lump sum for recast. Example: $50,000 lump sum.
- Enter new rate and costs for refinance. Example: New rate 4%, costs $9,000.
- Compare monthly savings and break-even. Calculator shows both options side-by-side. Recast $350 drop 1 month break-even vs refinance $500 drop 18 months break-even. Choose based on stay duration.
Results are estimates. Consult lender for exact quotes.
Frequently Asked Questions
Should I recast or refinance my mortgage?
Recast your mortgage if you have $10k+ lump sum, satisfied with current rate, and want lower payment with $300 fee. Refinance if rates dropped 0.5-1%, want shorter term, or need cash-out. Recast costs 98% less.
Is recast cheaper than refinance?
Recast is cheaper than refinance. Recast fee $150-$500 vs refinance costs 2-5% of loan. On $300k, recast costs $300 vs refinance $6k-$15k. Recast saves $5,700-$14,700 upfront. Refinance only wins if rate drops enough to recover costs in 24-60 months.
Can you recast an FHA loan?
You cannot recast an FHA loan. Recasting is only available for conventional loans, not FHA, VA, or USDA. FHA borrowers must refinance to lower payment. VA also requires refinance, not recast.
Does recasting a mortgage hurt credit?
Recasting a mortgage does not hurt credit. No credit check required. No new loan opened. Refinance requires credit check and may drop score 5-10 points temporarily. Recast keeps credit unchanged.
How much does a mortgage recast cost?
Mortgage recast costs $150-$500 fee. Some lenders charge $250. Fee covers administrative cost to recalculate amortization. No appraisal required. Compare to refinance 2-5% costs.
What is the minimum lump sum for mortgage recast?
Minimum lump sum for mortgage recast is typically $10,000. Some lenders require $5,000. Amount must be substantial to justify recalculation. Smaller amounts apply as principal-only payment without recast.
Does recasting reset your loan term?
Recasting does not reset your loan term. Term stays same. Payment drops due to lower balance. Refinance can change term. If 20 years left, recast keeps 20 years. Refinance can extend to 30 years or shorten to 15.
Can I recast and refinance later?
You can recast and refinance later. Recast first to lower payment with $300 fee, then refinance when rates drop. No restriction. But if refinancing soon, skip recast and put lump sum toward refinance costs. Each refinance resets term.
Calculate Recast Vs Refinance Savings
Enter current loan, lump sum, and new rate in Payoof Recast Vs Refinance Calculator. See payment drop, total interest saved, and break-even months for both options. Compare side-by-side. Download report. No email required.
Launch Recast Vs Refinance Calculator | Mortgage Recast Calculator | Refinance Break-Even Calculator

Disclaimer: Recasting vs refinancing educational only. Costs $150-$500 recast vs 2-5% refinance, escrow 2-6 months upfront, PMI removal rules vary. Consult lender. All stats linked.