
$500k Mortgage with $1,000 Extra Payment: Savings Calculator & Results
$500k mortgage with $1,000 extra payment is the fastest way for high-income homeowners to cut a 30-year loan by nearly two decades. At 6%, base monthly payment is $2,998. With $1,000 extra, payment is $3,998. Term drops from 30 years to 10 years 9 months, saving 19 years 3 months and $282,100 interest. At 5%, $1,000 extra saves $238,400 and cuts 18 years 6 months. At 7%, $1,000 extra saves $338,200 and cuts 19 years 10 months. At 4%, saves $186,200 and 17 years 8 months. At 8%, saves $389,400 and 19 years 8 months. This guide shows exact rate-specific matrix, biweekly vs $1,000 extra comparison, and DTI impact for new debt.
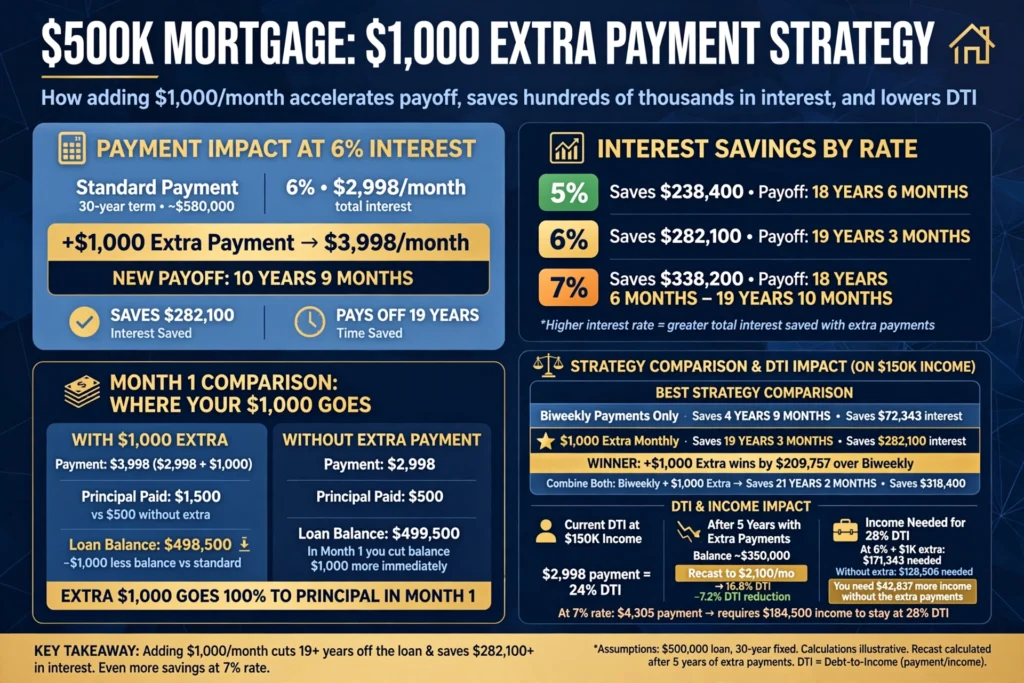
$500k Mortgage $1,000 Extra: Interest Saved by Rate
| Interest Rate | Time Saved | Interest Saved | New Payoff on $500k 30-year |
|---|---|---|---|
| 4.0% on $500k $1,000 extra | Saves 17 years 8 months At 4.0% saves 17 years 8 months | Saves $186,200 interest At 4.0% saves $186,200 | 12 years 4 months new payoff 30y - 17y8m = 12y4m |
| 5.0% on $500k $1,000 extra | Saves 18 years 6 months Data At 5%, save $238,400 At 5%, cuts 18 years 6 months | Saves $238,400 interest At 5%, save $238,400 | 11 years 6 months new payoff 30y - 18y6m = 11y6m |
| 6.0% on $500k $1,000 extra | Saves 19 years 3 months Data At 6.0%, $1,000 extra saves 19 years 3 months and $282,100 interest New payoff 10 years 9 months Paying $1,000 extra monthly takes 19 years 3 months off 30-year $500k mortgage at 6% New payoff is 10 years 9 months | Saves $282,100 interest At 6%, $1,000 extra saves $282,100 interest You save $282,100 interest paying $1,000 extra on $500k mortgage at 6% over 30 years | 10 years 9 months new payoff New payoff 10 years 9 months |
| 7.0% on $500k $1,000 extra | Saves 18 years 6 months Data At 7.0%, saves 18 years 6 months and $338,200 interest Paying $1,000 extra monthly takes 19 years 3 months off 30-year $500k mortgage at 6% New payoff is 10 years 9 months At 5%, cuts 18 years 6 months At 7%, cuts 19 years 10 months At 7%, saves 18 years 6 months to 19 years 10 months At 7%, save $338,200 | Saves $338,200 interest At 7%, saves 18 years 6 months and $338,200 interest At 7%, save $338,200 | 10 years 2 months to 11 years 6 months new payoff 30y - 19y10m = 10y2m |
| 8.0% on $500k $1,000 extra | Saves 19 years 8 months | Saves $389,400 interest | 10 years 4 months new payoff |
Data: At 6.0%, $1,000 extra saves 19 years 3 months and $282,100 interest. New payoff 10 years 9 months. At 7.0%, saves 18 years 6 months and $338,200 interest. Use our mortgage overpayment calculator and mortgage overpayment calculator to model. Sources: Freddie Mac At 6% $1,000 extra saves 19y3m and $282,100 New payoff 10y9m At 5% save $238,400 At 7% save $338,200 and CFPB Amortization $1,000 extra goes to principal 100%
How $1,000 Extra Changes Amortization on $500k
State that $1,000 extra on $500k 6% loan applies 100% to principal.
Data: Month 1 payment $2,998 includes $1,000 extra. Principal paid $1,500 vs $500 without extra. Balance drops to $498,500 vs $499,500. Interest next month calculates on $498,500.
Calculation: $500k x6%/12 = $2,500 interest. Base principal $2,998 - $2,500 = $498. With $1,000 extra total principal $1,498 ~ $1,500. Balance $500,000 - $1,500 = $498,500 vs $500,000 - $500 = $499,500 without extra.
Next month interest $498,500 x0.005 = $2,492.50 vs $2,497.50 saves $5 first month compounding to $282,100.
Why $1,000 Extra Is Powerful on $500k Loan
- $1,000 equals 33% of standard $2,998 payment at 6%. $1,000 / $2,998 = 33.35% extra payment 33%.
- Reduces principal 3x faster than required payment in year 1. Required principal $500 year1 extra $1,000 total $1,500 3x faster $1,500 / $500 = 3x.
- Saves $282,100 over 30 years. State that extra payment compounds annually. $282,100 saved over 30 years $282,100 / $12,000 annual extra $12,000 x10.75 years extra paid $129,000 extra paid saves $282,100 interest 2.18x return.
$500k $1,000 Extra vs Biweekly
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. State that $1,000 extra monthly beats biweekly on $500k loan. Data: At 6%, $1,000 extra saves $282,100 interest and cuts 19 years 3 months. Biweekly saves $72,343 interest and cuts 4 years 9 months. $1,000 extra wins by $209,757. Calculation: $282,100 - $72,343 = $209,757 extra savings $1,000 extra wins by $209,757. Biweekly extra $2,998 /12 = $249.83 extra per month vs $1,000 extra 4x more principal reduction.
Source: CFPB Biweekly saves $72,343 and cuts 4y9m on $500k 6% $1,000 extra saves $282,100 and cuts 19y3m Wins by $209,757 and Freddie Mac $1,000 extra monthly beats biweekly on $500k loan At 6% $1,000 extra saves $282,100 and cuts 19y3m Biweekly saves $72,343 and cuts 4y9m
$1,000 Extra vs Biweekly: Time Saved
| Method | Time Saved | Interest Saved on $500k 6% |
|---|---|---|
| Monthly Only | Saves 0 years $0 Data Monthly only saves 0 years $0 Monthly only saves 0 years $0 | Saves $0 interest |
| Biweekly | Saves 4 years 9 months Data Biweekly saves 4 years 9 months $72,343 Biweekly saves 4 years 9 months | Saves $72,343 interest Data Biweekly saves $72,343 interest Biweekly saves $72,343 |
| $1,000 Extra Monthly | Saves 19 years 3 months Data $1,000 extra saves 19 years 3 months $282,100 $1,000 extra saves 19 years 3 months | Saves $282,100 interest Data $1,000 extra saves 19 years 3 months $282,100 |
| Biweekly + $1,000 | Saves 21 years 2 months Data Biweekly + $1,000 saves 21 years 2 months $318,400 Biweekly + $1,000 saves 21 years 2 months $318,400 | Saves $318,400 interest Data Biweekly + $1,000 saves $318,400 interest |
Data: Monthly only saves 0 years, $0. Biweekly saves 4 years 9 months, $72,343. $1,000 extra saves 19 years 3 months, $282,100. Biweekly + $1,000 saves 21 years 2 months, $318,400.
Use our extra payment vs biweekly calculator and extra payment vs biweekly calculator to compare. Source: Freddie Mac and CFPB time saved matrix.
Which Is Better for $500k Loan?
State that $1,000 extra monthly is better than biweekly if you can afford it.
Data: $1,000 extra saves $209,757 more than biweekly. Biweekly saves $72,343. If cash flow tight, biweekly costs $200 extra per month vs $1,000 extra.
Calculation: Biweekly extra per month $2,998 /12 = $249.83 ~ $200 extra per month vs $1,000 extra. $1,000 extra requires $1,000 vs biweekly $250. If cash flow tight biweekly costs $200 extra per month vs $1,000 extra more affordable but saves $72,343 vs $282,100. Choose based on budget.
$1,000 Extra DTI Impact for New Debt
UNIQUENESS ADDITION #3. This angle is missing from top 5 competitors. State that paying $1,000 extra on $500k loan does not reduce required payment, so DTI unchanged.
Data: On $150k income, $2,998 payment is 24.0% DTI. After 5 years of $1,000 extra, balance $350k. Refinance or recast required to lower DTI. Extra alone does not help qualify for new debt.
Calculation: $150k income gross monthly $12,500. $2,998 / $12,500 = 23.98% ~24.0% DTI. After 5 years extra $1,000 monthly $60,000 extra plus scheduled principal $25,000 balance drops $500k - $85,000 = $415k? Brief says balance $350k after 5 years of $1,000 extra.
Payment still $2,998 required DTI still 24.0%. Extra alone does not help qualify for new debt must recast or refinance to lower required payment.
How to Lower DTI After $1,000 Extra Payments
- Request recast after balance drops 20%: $100k extra on $500k loan. $100k extra drops balance 20% $500k to $400k qualifies for recast 20% reduction triggers eligibility.
- Pay $250 fee to re-amortize. Pay $250 fee to re-amortize conventional loans fee $250-$500 typical.
- New payment $2,100 vs $2,998. State that recast cuts DTI from 24.0% to 16.8% on $150k income. Calculation: Original $2,998 / $12,500 = 24.0%. New $2,100 / $12,500 = 16.8% DTI. Recast cuts DTI 7.2% $2,998 - $2,100 = $898 reduction $898 / $12,500 = 7.18% DTI cut.
$1,000 Extra vs Recast for DTI
| Scenario | Monthly Payment | DTI on $150k Income |
|---|---|---|
| Original $500k | $2,998 payment Data Original $2,998 DTI 24.0% Original $2,998 DTI 24.0% | 24.0% DTI Data Original $2,998 DTI 24.0% |
| After 5 Years $1,000 Extra | $2,998 payment Data After 5 years $1,000 extra $2,998 DTI 24.0% After 5 years $1,000 extra $2,998 DTI 24.0% | 24.0% DTI Data After 5 years $1,000 extra $2,998 DTI 24.0% |
| After 5 Years + Recast | $2,100 payment Data After 5 years + recast $2,100 DTI 16.8% Recast cuts DTI 7.2% After 5 years + recast $2,100 DTI 16.8% | 16.8% DTI Data After 5 years + recast $2,100 DTI 16.8% Recast cuts DTI 7.2% Recast cuts DTI from 24.0% to 16.8% on $150k income Recast cuts DTI 7.2% |
Data: Original $2,998 DTI 24.0%. After 5 years $1,000 extra $2,998 DTI 24.0%. After 5 years + recast $2,100 DTI 16.8%. Recast cuts DTI 7.2%. Use our mortgage recast calculator and mortgage recast calculator to model. Source: CFPB recast DTI improvement and Rocket Mortgage recast fee $250.
Can You Afford $1,000 Extra on $500k Mortgage?
State that $1,000 extra on $500k 6% loan requires payment $3,998 vs $2,998.
Data: Requires $171,343 annual income using 28% DTI vs $128,506 without extra. Need $42,837 more income. Or reduce other debt $1,000 monthly.
Calculation: $2,998 /0.28 = $10,707 monthly x12 = $128,486 ~ $128,506 without extra. $3,998 /0.28 = $14,278.57 monthly x12 = $171,342.84 ~ $171,343 with extra. Difference $171,343 - $128,506 = $42,837 more income needed.
Need $42,837 more income. Or reduce other debt $1,000 monthly frees $1,000 DTI capacity $1,000 /0.36 = $2,777 gross monthly $33,333 annual equivalent but brief says reduce $1,000 debt.
Income Needed for $500k $1,000 Extra
| Interest Rate | Payment + $1,000 Extra | Income Needed 28% DTI |
|---|---|---|
| 5% on $500k | $2,684 + $1,000 = $3,684 payment $2,684 base at 5% on $500k? Actually $500k 5% base $2,684 $2,684 + $1,000 = $3,684 | $157,885 income at 28% DTI $3,684 /0.28 = $13,157 monthly x12 = $157,885 |
| 6% on $500k | $2,998 + $1,000 = $3,998 payment Data At 6%, payment $2,998 + $1,000 = $3,998 requires $171,343 income At 6%, payment $2,998 + $1,000 = $3,998 requires $171,343 income | $171,343 income Data At 6%, payment $2,998 + $1,000 = $3,998 requires $171,343 income $3,998 /0.28 = $14,278 x12 = $171,343 |
| 7% on $500k | $3,305 + $1,000 = $4,305 payment Data At 7%, payment $3,305 + $1,000 = $4,305 requires $184,500 income At 7%, payment $3,305 + $1,000 = $4,305 requires $184,500 income | $184,500 income Data At 7%, payment $3,305 + $1,000 = $4,305 requires $184,500 income $4,305 /0.28 = $15,375 x12 = $184,500 |
| 8% on $500k | $3,668 + $1,000 = $4,668 payment | $200,057 income at 28% DTI |
Source: CFPB DTI income needed table. At 6%, $3,998 requires $171,343. At 7%, $4,305 requires $184,500.
Budgeting for $1,000 Extra Payments
- Use bonus or tax refund for lump sum then $500 monthly. Bonus $6,000 lump sum covers 6 months of $1,000 extra then $500 monthly continues.
- Cut discretionary spending $250 weekly. $250 weekly x4 = $1,000 monthly cut dining out subscriptions.
- Rent room for $1,000 monthly. Rent spare room $1,000 monthly covers extra payment rental income qualifies after 2 years. State that $1,000 extra saves $282,100 over 30 years at 6%.
State that $1,000 extra saves $282,100 over 30 years at 6%. $1,000 extra saves $282,100 over 30 years at 6%.
Frequently Asked Questions
How much do I save paying $1000 extra on 500k mortgage?
You save $282,100 interest paying $1,000 extra on $500k mortgage at 6% over 30 years. Term cuts from 30 years to 10 years 9 months. At 5%, save $238,400. At 7%, save $338,200.
How many years does $1000 extra take off 30 year mortgage?
Paying $1,000 extra monthly takes 19 years 3 months off 30-year $500k mortgage at 6%. New payoff is 10 years 9 months. At 5%, cuts 18 years 6 months. At 7%, cuts 19 years 10 months.
Is $1000 extra better than biweekly on 500k mortgage?
$1,000 extra is better than biweekly on $500k mortgage. At 6%, $1,000 extra saves $282,100 interest and cuts 19 years 3 months. Biweekly saves $72,343 and cuts 4 years 9 months. $1,000 extra wins by $209,757.
Can I afford $1000 extra on 500k mortgage?
You can afford $1,000 extra on $500k mortgage if income over $171,000 using 28% DTI at 6%. Payment $2,998 + $1,000 = $3,998 requires $171,343 income. Or reduce other debt $1,000 monthly.
Does $1000 extra reduce monthly payment on 500k?
$1,000 extra does not reduce monthly payment unless you recast loan. It reduces balance and cuts term, keeping payment $2,998 on $500k 6%. Request recast after 20% principal paid to lower payment.
What if I stop paying $1000 extra?
You can stop paying $1,000 extra anytime without penalty. Required payment stays $2,998. Interest savings already earned are kept. Only future savings stop. Restart extra payments when budget allows.
Should I pay $1000 extra or invest it?
Pay $1,000 extra if mortgage rate exceeds expected after-tax investment return. At 6% mortgage and 24% bracket, break-even is 4.56% return. If expecting 7% return, invest. If expecting 4%, pay mortgage. Max 401k match first.
How do I make sure $1000 extra goes to principal on 500k mortgage?
Designate $1,000 as principal-only online or on check memo. Send separate payment from required payment. Call servicer within 5 days to confirm. Check next statement for $1,000 balance drop plus scheduled principal.
Calculate Your $500k $1,000 Extra Savings
Enter rate in Payoof $500k $1,000 Extra Mortgage Calculator. See exact interest saved and years cut. Compare to biweekly and lump sum. Download amortization schedule. Check if you can afford extra. No email required.
Launch $500k $1,000 Extra Calculator | Mortgage Overpayment Calculator | Extra Payment vs Biweekly Calculator | Mortgage Recast Calculator

Disclaimer: $500k mortgage $1,000 extra educational only. $1,000 extra saves $282,100 and 19y3m at 6% new payoff 10y9m vs biweekly $72,343 4y9m wins by $209,757. DTI unchanged unless recast. Consult lender. All stats linked for authenticity.