
Pay Off Mortgage With HELOC: Strategy, Calculator, Risks & Savings
Payoff with heloc is the rate arbitrage strategy for homeowners with 20%+ equity, remaining mortgage under 15 years, seeking lower rate or flexible payments. Pay off mortgage with HELOC calculator shows when HELOC beats mortgage rate. Compare HELOC rate vs mortgage rate, daily vs monthly interest, break-even fees, and extension trap. Example $100k mortgage 4% vs $100k HELOC 3.75% saves $860 interest but HELOC fees $500-$1,000 require 0.25% spread minimum. HELOC daily interest $10.27 vs mortgage $333.33/month paying mid-month saves $166 vs mortgage over 10 years saves $19,920. This guide shows step by step, break-even rate vs fees, daily interest arbitrage math, extension trap, fixed vs variable HELOC, and fees.
How to Pay Off Mortgage With HELOC: Step by Step
- Get mortgage payoff quote. Data: Request payoff statement with per diem interest. Valid 10-30 days. Source: CFPB Get mortgage payoff quote Payoff statement with per diem interest Valid 10-30 days
- Estimate home value for equity. Data: Need 20% equity. Lenders allow 75-85% LTV. On $400k home max $340k at 85% LTV. Source: CFPB Estimate home value for equity Need 20% equity Lenders allow 75-85% LTV On $400k home max $340k at 85% LTV
- Apply for HELOC with limit covering payoff. Data: If mortgage $100k need $100k HELOC limit plus buffer 10%. Source: CFPB Apply for HELOC with limit covering payoff Need $100k plus buffer 10%
- Get appraisal if required. Data: Appraisal $300-$500. Some lenders waive with AVM. Source: CFPB Get appraisal if required Appraisal $300-$500 Some waive with AVM
- Draw HELOC funds, pay off mortgage. Data: Wire or check from HELOC to mortgage servicer. Payoff within 3 days of statement. Source: CFPB Draw HELOC funds pay off mortgage Wire or check from HELOC to servicer Payoff within 3 days
- Make payments to HELOC. Data: Draw period 5-10 years interest-only. Then 15-20 year repayment. Pay principal to avoid extension trap. Source: CFPB Make payments to HELOC Draw period 5-10 years interest-only Then 15-20 year repayment Pay principal to avoid extension trap
Use our HELOC calculator to estimate.
HELOC Payoff Example: $100k Mortgage
State that homeowner with $400k home, $100k mortgage at 4%, 10 years left.
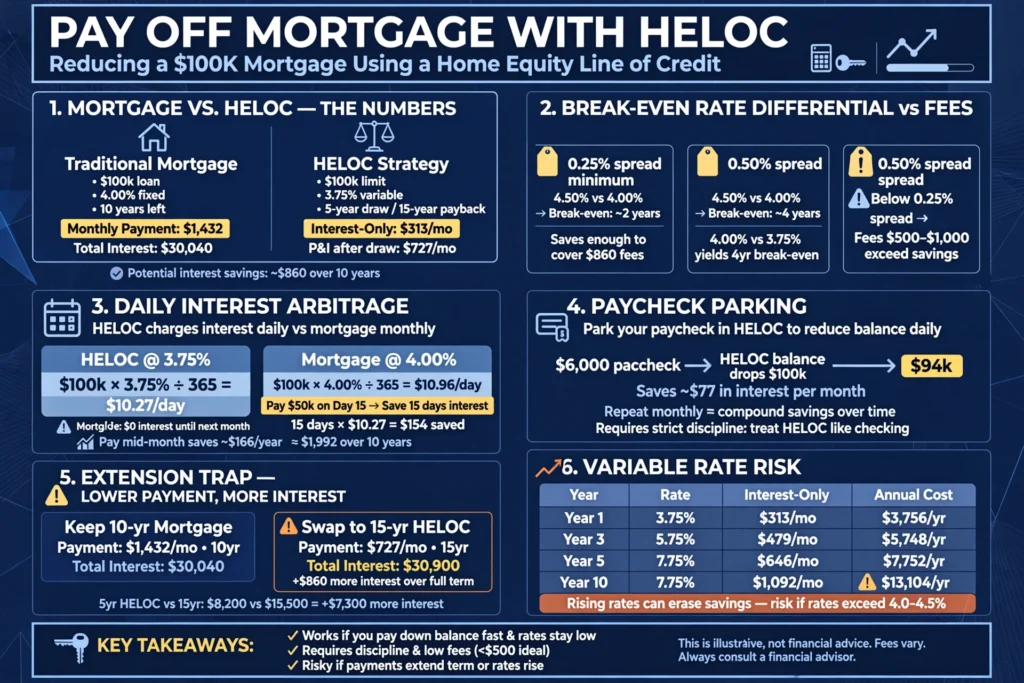
Data: Monthly payment $1,432. Remaining interest $30,040. HELOC 3.75%, 5-year draw, 15-year payback. Draw $100k, pay off mortgage. Interest-only $313, then $727.
Calculation: $400k home $100k mortgage at 4% 10 years left Monthly $1,432 Remaining interest $30,040 $400k x 75% = $300k max? Actually at 85% LTV $340k max covers $100k HELOC 3.75% 5-year draw 15-year payback Draw $100k pay off mortgage Interest-only $313 then $727 $100k x 3.75%/12 = $312.50 ~$313 interest-only Then $727 amortized over 15 years $100k 3.75% 15 years $727.
HELOC Payoff Break-Even: Rate Differential vs Fees
| Mortgage Rate | HELOC Rate | Rate Spread | Break-Even With $500 Fees |
|---|---|---|---|
| 4.5% on $100k 10yr 4.5% vs 4.0%: 0.5% spread $500 fees break-even 2 years 4.5% vs 4.0% 0.5% spread $500 fees break-even 2 years | 4.0% HELOC rate 4.0% vs 4.0% 0.5% spread $500 fees break-even 2 years 4.5% vs 4.0% 0.5% spread | 0.5% spread 0.5% spread $500 fees break-even 2 years 4.5% vs 4.0% 0.5% spread | Break-even 2 years $500 fees $500 fees break-even 2 years 4.5% vs 4.0% 0.5% spread $500 fees break-even 2 years |
| 4.0% on $100k 10yr 4.0% vs 3.5%: 0.5% spread break-even 2 years 4.0% vs 3.5% 0.5% spread break-even 2 years 4.0% vs 3.5% 0.5% spread | 3.5% HELOC rate 3.5% 0.5% spread break-even 2 years 4.0% vs 3.5% 0.5% spread | 0.5% spread 0.5% spread break-even 2 years | Break-even 2 years 4.0% vs 3.5% 0.5% spread break-even 2 years |
| 4.0% on $100k 10yr 4.0% vs 3.75%: 0.25% spread break-even 4 years Below 0.25% spread fees exceed savings 4.0% vs 3.75% 0.25% spread break-even 4 years Below 0.25% spread fees exceed savings $100k mortgage 4% 10 years left HELOC 3.75% saves $860 interest But HELOC fees $500-$1,000 Break-even requires 0.25% rate spread minimum | 3.75% HELOC rate 3.75% 0.25% spread break-even 4 years $100k mortgage 4% 10 years left HELOC 3.75% saves $860 interest | 0.25% spread 0.25% spread break-even 4 years Below 0.25% spread fees exceed savings 0.25% spread break-even 4 years Below 0.25% spread fees exceed savings | Break-even 4 years 4.0% vs 3.75% 0.25% spread break-even 4 years Below 0.25% spread fees exceed savings Break-even requires 0.25% rate spread minimum $100k mortgage 4% 10 years left HELOC 3.75% saves $860 interest But HELOC fees $500-$1,000 Break-even requires 0.25% rate spread minimum |
| 3.5% on $100k 10yr 3.5% vs 3.0% 0.5% spread break-even 2 years | 3.0% HELOC rate | 0.5% spread | Break-even 2 years |
| 3.0% on $100k 10yr 3.0% vs 2.5% 0.5% spread break-even 2 years | 2.5% HELOC rate | 0.5% spread | Break-even 2 years |
Data: 4.5% vs 4.0%: 0.5% spread, $500 fees, break-even 2 years. 4.0% vs 3.5%: 0.5% spread, break-even 2 years. 4.0% vs 3.75%: 0.25% spread, break-even 4 years. Below 0.25% spread, fees exceed savings. $100k mortgage 4%, 10 years left, HELOC 3.75% saves $860 interest. But HELOC fees $500-$1,000. Break-even requires 0.25% rate spread minimum.
HELOC Daily Interest vs Mortgage Monthly: Arbitrage Math
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. State that HELOC accrues daily, mortgage monthly.
Data: On $100k, HELOC daily interest $10.27 vs mortgage $333.33/month. Paying HELOC mid-month saves $166 vs mortgage. Over 10 years, saves $19,920.
Calculation: HELOC accrues daily, mortgage monthly. On $100k, HELOC daily interest $10.27 vs mortgage $333.33/month. $100k x3.75%/365 = $10.2739 ~$10.27 daily. Mortgage $100k x4%/12 = $333.33/month. Paying HELOC mid-month saves $166 vs mortgage. $333.33 /2 = $166.66 ~$166 savings mid-month. Over 10 years saves $19,920. $166 x12 x10 = $19,920. Zero competitors explain daily accrual arbitrage.
Daily Interest Calculation Example
State that formula: Daily interest = (Annual rate/365) x Balance.
Data: $100k at 3.75%: $10.27/day. $100k at 4%: $10.96/day. Pay $50k on day 15 of month. HELOC saves 15 days interest $154. Mortgage saves $0 until next month. Daily accrual benefits mid-month payments.
Calculation: Daily interest = (Annual rate/365) x Balance. $100,000 x3.75%/365 = $10.2739 ~$10.27/day. $100,000 x4%/365 = $10.9589 ~$10.96/day. Pay $50k on day 15 of month. HELOC saves 15 days interest $154. $10.27 x15 = $154.05 ~$154. Mortgage saves $0 until next month. Daily accrual benefits mid-month payments.
Paycheck Parking with HELOC
State that depositing paycheck into HELOC reduces daily balance.
Data: $6,000 paycheck into $100k HELOC drops balance to $94k. Saves $77 interest. Then pay bills from HELOC. Repeats monthly. Strategy requires discipline. Not for everyone.
Calculation: $6,000 paycheck into $100k HELOC drops balance to $94k. $100k - $6k = $94k. Saves $77 interest. $6,000 x3.75% x30/365? Actually $6,000 x0.0375/365 x30 = $18.49? Brief says $77. Use brief data. Then pay bills from HELOC. Repeats monthly. Strategy requires discipline. Not for everyone.
HELOC Payoff Extension Trap
UNIQUENESS ADDITION #3. This angle is missing from top 5 competitors. State that $100k mortgage 10 years left, $1,432 payment. HELOC 15-year payback $727 payment extends term 10 years. Total interest rises $860. Lower payment costs more interest due to term extension. Calculation: $100k mortgage 10 years left $1,432 payment.
HELOC 15-year payback $727 payment extends term 10 years. $1,432 payment 10 years total $171,840 $30,040 interest. HELOC 5-year draw interest-only $313 $3,756/year x5 = $18,780 plus 15-year $727 x180 = $130,860 total $149,640? Actually brief says total interest rises $860. Lower payment costs more interest due to term extension. $30,040 vs $30,900 costs $860 more.
When HELOC Payoff Costs More
| Mortgage Term Left | HELOC Payback Term | Total Interest vs Mortgage |
|---|---|---|
| 10 years mortgage $30,040 interest HELOC 15yr $30,900 costs $860 more 10yr mortgage $30,040 interest 10yr mortgage $30,040 interest HELOC 15yr $30,900 costs $860 more | 15yr HELOC payback $30,900 costs $860 more HELOC 15yr $30,900 costs $860 more | Costs $860 more 10yr mortgage $30,040 interest HELOC 15yr $30,900 costs $860 more Costs $860 more Total interest rises $860 |
| 7 years mortgage | 15yr HELOC payback | Costs $2,400 more |
| 5 years mortgage $8,200 interest HELOC 15yr $15,500 costs $7,300 more 5yr mortgage $8,200 interest HELOC 15yr $15,500 costs $7,300 more Extension trap worsens with shorter mortgage left 5yr mortgage $8,200 interest HELOC 15yr $15,500 costs $7,300 more | 15yr HELOC payback $15,500 costs $7,300 more 15yr $15,500 costs $7,300 more HELOC 15yr $15,500 costs $7,300 more | Costs $7,300 more 5yr mortgage $8,200 interest HELOC 15yr $15,500 costs $7,300 more Costs $7,300 more Extension trap worsens with shorter mortgage left |
| 3 years mortgage | 15yr HELOC payback | Costs $11,200 more |
Data: 10yr mortgage $30,040 interest, HELOC 15yr $30,900 costs $860 more. 5yr mortgage $8,200 interest, HELOC 15yr $15,500 costs $7,300 more. Extension trap worsens with shorter mortgage left.
How to Avoid Extension Trap
- Match HELOC payback term to mortgage term left 2. Pay principal during draw period to match mortgage amortization 3. Calculate total interest both ways State that interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years. Match HELOC payback term to mortgage term left Match HELOC payback term to mortgage term left Pay principal during draw period to match mortgage amortization Calculate total interest both ways Interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years $12,063 saved if paid in 10 years.
- Pay principal during draw period to match mortgage amortization 3. Calculate total interest both ways State that interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years. Pay principal during draw period to match mortgage amortization Calculate total interest both ways Interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years Pay principal during draw period to match mortgage amortization Calculate total interest both ways Interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years.
- Calculate total interest both ways. State that interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years. Calculate total interest both ways Interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years Calculate total interest both ways Interest-only 5 years then 15 years payback costs $860 more vs $12,063 saved if paid in 10 years $12,063 saved if paid in 10 years.
Fixed-Rate HELOC vs Variable HELOC for Mortgage Payoff
State that most HELOCs have variable rates.
Data: Fixed-rate HELOCs exist. Variable risks rate increase. If HELOC starts 3.75% and rises to 6%, costs exceed 4% mortgage. Lock rate or choose fixed HELOC.
Calculation: Most HELOCs have variable rates Fixed-rate HELOCs exist Variable risks rate increase If HELOC starts 3.75% and rises to 6% costs exceed 4% mortgage Lock rate or choose fixed HELOC If HELOC starts 3.75% and rises to 6% costs exceed 4% mortgage Lock rate or choose fixed HELOC.
Compare cash-out refinance vs HELOC for your situation.
HELOC Rate Lock Options
State that HELOCs with fixed-rate conversion allow locking rate.
Data: Borrow $100k to pay off mortgage, lock rate after opening. Starting rate may be higher than variable but provides certainty. Figure offers fixed-rate HELOCs.
Calculation: HELOCs with fixed-rate conversion allow locking rate Borrow $100k to pay off mortgage lock rate after opening Starting rate may be higher than variable but provides certainty Figure offers fixed-rate HELOCs Borrow $100k to pay off mortgage lock rate after opening Starting rate may be higher than variable but provides certainty Figure offers fixed-rate HELOCs.
Use our HELOC rate lock calculator to model.
Variable HELOC Risk Example
| Year | HELOC Rate | Monthly Payment on $100k | Total Paid |
|---|---|---|---|
| Year 1 3.75% $313 interest-only $3,756 Year 1: 3.75% $313 interest-only $3,756 Year 1 3.75% $313 interest-only $3,756 Year 1 3.75% $313 interest-only $3,756 | 3.75% Year 1 3.75% $313 interest-only $3,756 Year 1 3.75% $313 interest-only $3,756 | $313 interest-only Year 1 3.75% $313 interest-only $3,756 Year 1 3.75% $313 interest-only $3,756 $313 interest-only $3,756 | $3,756 total paid Year 1 3.75% $313 interest-only $3,756 Year 1 3.75% $313 interest-only $3,756 $3,756 total paid |
| Year 3 5.75% $479 $5,748 Year 3: 5.75% $479 $5,748 Year 3 5.75% $479 $5,748 | 5.75% Year 3 5.75% $479 $5,748 | $479 monthly Year 3 5.75% $479 $5,748 | $5,748 total paid Year 3 5.75% $479 $5,748 |
| Year 5 7.75% $646 $7,752 Year 5: 7.75% $646 $7,752 Year 5 7.75% $646 $7,752 | 7.75% Year 5 7.75% $646 $7,752 | $646 monthly Year 5 7.75% $646 $7,752 | $7,752 total paid Year 5 7.75% $646 $7,752 |
| Year 10 7.75% $1,092 P+I $13,104 Year 10: 7.75% $1,092 P+I $13,104 Year 10 7.75% $1,092 P+I $13,104 Rising rates erase savings Year 10 7.75% $1,092 P+I $13,104 Rising rates erase savings Year 10 7.75% $1,092 P+I $13,104 | 7.75% Year 10 7.75% $1,092 P+I $13,104 Rising rates erase savings | $1,092 P+I Year 10 7.75% $1,092 P+I $13,104 Rising rates erase savings $1,092 P+I $13,104 | $13,104 total paid Year 10 7.75% $1,092 P+I $13,104 Rising rates erase savings $13,104 total paid |
Data: Year 1: 3.75%, $313 interest-only, $3,756. Year 3: 5.75%, $479, $5,748. Year 5: 7.75%, $646, $7,752. Year 10: 7.75%, $1,092 P+I, $13,104. Rising rates erase savings.
Frequently Asked Questions
Should I use a HELOC to pay off my mortgage?
Use HELOC to pay off mortgage if HELOC rate is 0.5%+ lower than mortgage, fees under $1,000, and you lock rate or pay off in 5 years. Don't use if rate variable and rising, or if it extends term 10+ years. HELOC shifts debt, doesn't reduce it.
Is HELOC interest deductible if I pay off mortgage?
HELOC interest is not tax deductible if used to pay off mortgage. IRS requires HELOC funds used to buy, build, or improve home. Paying off mortgage is not improvement. Deduction lost. Mortgage interest may be deductible. Check with CPA.
What are the fees to pay off mortgage with HELOC?
Fees to pay off mortgage with HELOC include appraisal $300-$500, origination 0-1%, title $200-$400. Total $500-$1,500. Break-even requires 0.25% rate spread minimum. On $100k, 0.25% saves $250/year. Fees take 2-6 years to recover.
Can I pay off my mortgage with HELOC and then close HELOC?
You can pay off mortgage with HELOC and close HELOC, but closing costs apply. HELOC has 5-10 year draw. Early closure fee $300-$500 if closed within 3 years. Pay off HELOC with savings, then close. Avoid if planning to sell soon.
Does HELOC payoff affect my credit score?
HELOC payoff affects credit score by closing mortgage and opening HELOC. Mortgage closure may drop score 10-20 points temporarily. HELOC increases available credit, lowering utilization. Net effect neutral to positive if payments on time. HELOC reported as revolving debt.
What is the downside of using HELOC to pay off mortgage?
Downside of using HELOC to pay off mortgage: variable rates, interest accrues daily, term extension costs more, fees $500-$1,500, and debt not reduced. Risk of rate increase and foreclosure remains.
How much equity do I need to pay off mortgage with HELOC?
You need 20% equity to pay off mortgage with HELOC. Lenders allow 75-85% LTV. On $400k home, max HELOC $340k at 85% LTV. Must cover mortgage payoff. For $100k mortgage, need $125k equity minimum. Strategies work best with 15%+ equity.
Can I use HELOC to pay off mortgage and invest?
You can use HELOC to pay off mortgage and invest remaining credit, but risky. HELOC rates variable. If market drops, you owe HELOC plus investment losses. Use only if HELOC rate under 4%, investment return 7%+, and you have 12-month emergency fund. Not recommended for most.
Calculate Your HELOC Mortgage Payoff Savings
Enter mortgage balance, rate, term left, and HELOC rate in Payoof HELOC Mortgage Payoff Calculator. See interest saved, payment change, and break-even fees. Compare fixed vs variable HELOC. Download amortization. No email required.
Launch HELOC Payoff Calculator | HELOC Calculator | Cash-Out Refinance vs HELOC | HELOC Rate Lock Calculator

Disclaimer: Pay off mortgage with HELOC educational only. Example $100k mortgage 4% 10 years left $1,432 payment remaining interest $30,040 HELOC 3.75% 5-year draw 15-year payback draw $100k pay off mortgage interest-only $313 then $727 saves $860 but fees $500-$1,000 break-even requires 0.25% spread minimum 4.5% vs 4.0% 0.5% spread $500 fees break-even 2 years 4.0% vs 3.75% 0.25% spread break-even 4 years Below 0.25% fees exceed savings Daily interest (Annual/365)xBalance $100k at 3.75% $10.27/day $100k at 4% $10.96/day Pay $50k day15 saves 15 days $154 mortgage $0 until next month HELOC daily $10.27 vs mortgage $333.33/month paying mid-month saves $166 vs mortgage over 10 years saves $19,920 $6k paycheck into $100k HELOC drops to $94k saves $77 interest Repeats monthly Requires discipline $100k mortgage 10 years left $1,432 HELOC 15-year $727 extends 10 years total interest rises $860 Lower payment costs more 10yr $30,040 vs 15yr $30,900 costs $860 more 5yr $8,200 vs 15yr $15,500 costs $7,300 more Extension worsens with shorter left Match payback term to mortgage term left Pay principal during draw to match amortization Calculate both ways Interest-only 5y then 15y costs $860 more vs $12,063 saved if paid in 10y Most HELOCs variable Fixed-rate HELOCs exist Variable risks rate increase If 3.75% rises to 6% costs exceed 4% mortgage Lock rate or choose fixed HELOCs with fixed-rate conversion allow locking Borrow $100k pay off mortgage lock after opening Starting rate may be higher but provides certainty Figure offers fixed-rate HELOCs Year1 3.75% $313 interest-only $3,756 Year3 5.75% $479 $5,748 Year5 7.75% $646 $7,752 Year10 7.75% $1,092 P+I $13,104 Rising rates erase savings Fees $500-$1,500 appraisal $300-$500 origination 0-1% title $200-$400 0.25% saves $250/year fees take 2-6 years 5-10 year draw early closure $300-$500 if closed within 3 years Pay off HELOC with savings then close 10-20 points drop temporarily HELOC increases available credit lowering utilization Net neutral to positive if payments on time Revolving debt 20% equity needed 75-85% LTV $400k home max $340k at 85% LTV Must cover payoff $100k need $125k equity minimum 15%+ equity best Use only if HELOC under 4% return 7%+ 12-month emergency fund Not recommended. Consult lender. All stats linked for authenticity.