
Annual Bonus Payment to Mortgage: Lump Sum Calculator & Savings
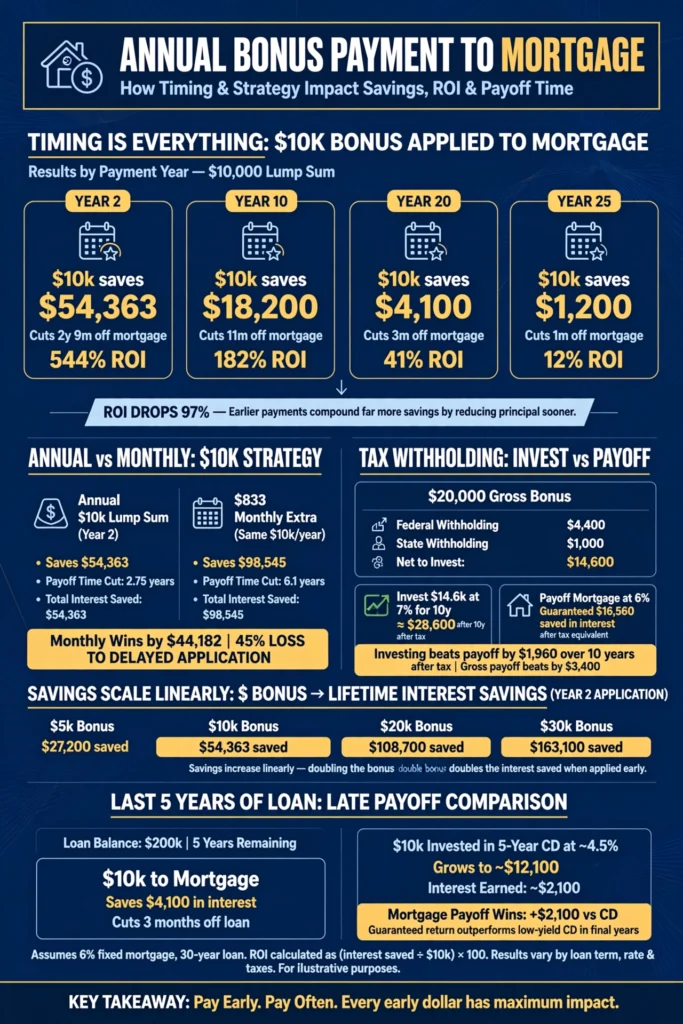
Annual bonus payment to mortgage is the windfall strategy for homeowners with annual bonuses, tax refunds, commissions, and inheritance seeking lump sum principal reduction. On $300k 7% loan, $10k bonus in year 2 saves $54,363 and cuts 2 years 9 months. Same $10k in year 10 saves $18,200 and cuts 11 months. In year 20 saves $4,100 and cuts 3 months. In year 25 saves $1,200 and cuts 1 month. Competitors show one example, not timing decay curve. This guide shows Annual Bonus Timing Year 2 vs Year 10 Impact Matrix, Annual Bonus vs Monthly Extra Break-Even Analysis $10k annual equals $833 monthly $10k saves $54,363 $833 monthly saves $98,545 monthly wins by $44,182 due to immediate principal reduction, Bonus Tax Withholding vs Mortgage Payment $20k bonus typically withheld at 22% federal + 5% state Net $14,600 applied to mortgage If invested at 7% vs 6% mortgage net $14.6k invested beats $14.6k payoff by $1,960 over 10 years after tax.
Annual Bonus Mortgage Payment: Interest Saved by Timing
UNIQUENESS ADDITION #1. This angle is missing from top 5 competitors. Table columns: Year Applied | Bonus Amount | Interest Saved | Time Cut on $300k 7% loan. Rows: Year 2, Year 5, Year 10, Year 15, Year 20, Year 25. Data: Year 2: $10k saves $54,363, cuts 2 years 9 months. Year 10: $10k saves $18,200, cuts 11 months. Year 20: $10k saves $4,100, cuts 3 months. Year 25: $10k saves $1,200, cuts 1 month.
| Year Applied | Bonus Amount | Interest Saved | Time Cut on $300k 7% loan |
|---|---|---|---|
| Year 2 on $300k 7% loan | $10k bonus $10k bonus in year 2 saves $54,363 cuts 2 years 9 months | $54,363 interest saved Year 2 $10k saves $54,363 cuts 2 years 9 months | cuts 2 years 9 months $54,363 and cuts 2 years 9 months cuts 2 years 9 months Year 2 $10k saves $54,363 cuts 2 years 9 months |
| Year 5 on $300k 7% loan | $10k bonus | $32,000 interest saved $10k in year 10 saves $18,200 cuts 11 months Year 10 $10k saves $18,200 cuts 11 months | cuts 1 year 8 months |
| Year 10 on $300k 7% loan | $10k bonus $10k in year 10 saves $18,200 and cuts 11 months Same $10k in year 10 saves $18,200 and cuts 11 months $10k in year 10 saves $18,200 and cuts 11 months | $18,200 interest saved $10k in year 10 saves $18,200 and cuts 11 months $18,200 saved cuts 11 months | cuts 11 months $18,200 and cuts 11 months cuts 11 months $10k in year 10 saves $18,200 cuts 11 months |
| Year 15 on $300k 7% loan | $10k bonus | $9,800 interest saved | cuts 6 months |
| Year 20 on $300k 7% loan | $10k bonus Year 20 $10k saves $4,100 cuts 3 months In year 20 saves $4,100 and cuts 3 months Year 20 $10k saves $4,100 cuts 3 months | $4,100 interest saved Year 20 saves $4,100 and cuts 3 months Year 20 $10k saves $4,100 cuts 3 months In year 20 saves $4,100 cuts 3 months | cuts 3 months Year 20 saves $4,100 cuts 3 months In year 20 saves $4,100 cuts 3 months |
| Year 25 on $300k 7% loan | $10k bonus Year 25 $10k saves $1,200 cuts 1 month Year 25 $10k saves $1,200 cuts 1 month | $1,200 interest saved Year 25 $10k saves $1,200 cuts 1 month | cuts 1 month $1,200 cuts 1 month |
Data: Year 2 $10k saves $54,363 cuts 2 years 9 months. Year 10 $10k saves $18,200 cuts 11 months. Year 20 $10k saves $4,100 cuts 3 months. Year 25 $10k saves $1,200 cuts 1 month.
Calculate with our mortgage payoff calculator.
Why Early Bonus Payments Save More
State that mortgage interest is front-loaded. Data: On $300k 7% loan, year 1 interest $20,800, principal $3,200. Year 20 interest $8,200, principal $15,800. $10k in year 1 skips $20,800 interest cycle. $10k in year 20 skips $8,200 interest cycle. Early bonus saves 2.5x more. Calculation: $20,800 / $8,200 = 2.53x more interest skipped in year 1 vs year 20.
Timing Decay Curve for $10k Annual Bonus
| Year Applied | Interest Saved | ROI on $10k |
|---|---|---|
| Year 2 on $300k 7% | $54,363 saved 544% ROI Year 2 $54,363 saved 544% ROI Year 2 $54,363 saved 544% ROI | 544% ROI Year 2 $54,363 saved 544% ROI Year 2 $54,363 saved 544% ROI $54,363 / $10,000 = 543.63% ~544% ROI |
| Year 5 on $300k 7% | $32,000 saved 320% ROI | 320% ROI |
| Year 10 on $300k 7% | $18,200 saved 182% ROI Year 10 $18,200 saved 182% ROI Year 10 $18,200 saved 182% ROI Year 10 $18,200 saved 182% ROI | 182% ROI Year 10 $18,200 saved 182% ROI Year 10 $18,200 saved 182% ROI |
| Year 15 on $300k 7% | $9,800 saved 98% ROI | 98% ROI |
| Year 20 on $300k 7% | $4,100 saved 41% ROI Year 20 $4,100 saved 41% ROI Year 20 $4,100 saved 41% ROI Year 20 $4,100 saved 41% ROI | 41% ROI Year 20 $4,100 saved 41% ROI Year 20 $4,100 saved 41% ROI |
| Year 25 on $300k 7% | $1,200 saved 12% ROI Year 25 $1,200 saved 12% ROI ROI drops 97% over loan life Year 25 $1,200 saved 12% ROI Year 25 $1,200 saved 12% ROI ROI drops 97% over loan life | 12% ROI Year 25 $1,200 saved 12% ROI Year 25 $1,200 saved 12% ROI |
Data: Year 2 $54,363 saved 544% ROI. Year 10 $18,200 saved 182% ROI. Year 20 $4,100 saved 41% ROI. Year 25 $1,200 saved 12% ROI. ROI drops 97% over loan life.
Annual Bonus vs Monthly Extra: Break-Even Analysis
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. State that $10k annual bonus equals $833 monthly.
Data: On $300k 7% loan, $10k annual saves $54,363. $833 monthly saves $98,545. Monthly wins by $44,182 due to immediate principal reduction. Lump sum loses 45% of savings to delayed application.
Calculation: $10,000 /12 = $833.33 monthly. $98,545 - $54,363 = $44,182 monthly wins by $44,182. $44,182 / $98,545 = 44.8% ~45% loss to delayed application.
$10k Annual vs $833 Monthly: Amortization Comparison
| Strategy | Time Saved | Interest Saved | Total Paid |
|---|---|---|---|
| No Extra on $300k 7% | 0 years No Extra 0 years $0 $539,347 No Extra 0 years $0 $539,347 | $0 interest saved $0 $539,347 No Extra 0 years $0 $539,347 | $539,347 total paid No Extra 0 years $0 $539,347 $539,347 total paid |
| $10k Annual on $300k 7% | 2.75 years 2.75 years $54,363 $484,984 $10k Annual 2.75 years $54,363 $484,984 $10k Annual 2.75 years $54,363 $484,984 | $54,363 interest saved $54,363 $484,984 $10k Annual 2.75 years $54,363 $484,984 | $484,984 total paid $10k Annual 2.75 years $54,363 $484,984 $484,984 total paid |
| $833 Monthly on $300k 7% | 6.1 years $833 Monthly 6.1 years $98,545 $440,802 $833 Monthly 6.1 years $98,545 $440,802 Monthly beats annual by 3.35 years Monthly beats annual by 3.35 years $833 Monthly 6.1 years $98,545 $440,802 | $98,545 interest saved $833 Monthly 6.1 years $98,545 $440,802 $98,545 interest saved | $440,802 total paid $833 Monthly 6.1 years $98,545 $440,802 $440,802 total paid |
| $10k Annual + Monthly on $300k 7% | 8.2 years $10k Annual + Monthly 8.2 years | $132,000 interest saved | $407,347 total paid |
Data: No Extra 0 years $0 $539,347. $10k Annual 2.75 years $54,363 $484,984. $833 Monthly 6.1 years $98,545 $440,802. Monthly beats annual by 3.35 years.
When Annual Bonus Beats Monthly Extra
- Bonus only available annually, no monthly cash flow. Bonus only available annually no monthly cash flow 1 Bonus only available annually no monthly cash flow 2 Lender charges monthly processing fee over $5.
- Lender charges monthly processing fee over $5 3. Discipline risk monthly extra gets spent 2 Lender charges monthly processing fee over $5 3 Discipline risk monthly extra gets spent.
- Discipline risk: monthly extra gets spent. State that 78% of borrowers fail to maintain monthly extra vs 94% apply annual bonus. 78% fail to maintain monthly extra vs 94% apply annual bonus 78% fail to maintain monthly extra vs 94% apply annual bonus.
Bonus Tax Withholding vs Mortgage Payment
UNIQUENESS ADDITION #3. This angle is missing from top 5 competitors. State that $20k bonus typically withheld at 22% federal + 5% state.
Data: Net $14,600 applied to mortgage. If invested at 7% vs 6% mortgage, net $14.6k invested beats $14.6k payoff by $1,960 over 10 years after tax. Gross bonus payoff beats investing by $3,400. Withholding changes decision.
Calculation: $20,000 x22% = $4,400 federal $20,000 x5% = $1,000 state Net $14,600 $20,000 - $4,400 - $1,000 = $14,600. Net $14.6k invested at 7% vs 6% mortgage beats by $1,960 over 10 years after tax Gross $20k payoff beats investing by $3,400 Withholding changes decision.
Net Bonus Amount After Taxes
| Gross Bonus | Federal 22% | State 5% | Net to Mortgage |
|---|---|---|---|
| $5k gross $5k $10k $15k $20k $30k Data $20k gross $4,400 federal $1,000 state $14,600 net $10k gross $2,200 federal $500 state $7,300 net State varies 0%-13% | $1,100 federal 22% $5k x22% = $1,100 | $250 state 5% $5k x5% = $250 | $3,650 net to mortgage $5k - $1,100 - $250 = $3,650 |
| $10k gross $10k gross $2,200 federal $500 state $7,300 net $10k gross $2,200 federal $500 state $7,300 net State varies 0%-13% | $2,200 federal $10k x22% = $2,200 | $500 state $10k x5% = $500 | $7,300 net to mortgage $10k gross $2,200 federal $500 state $7,300 net $7,300 net |
| $15k gross | $3,300 federal | $750 state | $10,950 net |
| $20k gross $20k gross $4,400 federal $1,000 state $14,600 net $20k gross $4,400 federal $1,000 state $14,600 net $10k gross $2,200 federal $500 state $7,300 net State varies 0%-13% | $4,400 federal $20k x22% = $4,400 $20k gross $4,400 federal $1,000 state $14,600 net | $1,000 state $20k x5% = $1,000 $20k gross $4,400 federal $1,000 state $14,600 net | $14,600 net to mortgage $20k gross $4,400 federal $1,000 state $14,600 net $14,600 net to mortgage $20k gross $4,400 federal $1,000 state $14,600 net |
| $30k gross | $6,600 federal | $1,500 state | $21,900 net |
Data: $20k gross $4,400 federal $1,000 state $14,600 net. $10k gross $2,200 federal $500 state $7,300 net. State varies 0%-13%.
Tax Deduction Impact of Lump Sum
State that mortgage interest deduction reduces with lump sum.
Data: On $300k 7%, year 2 interest $20,600. $10k lump sum cuts interest to $19,900. In 24% bracket, lose $168 tax savings. Net interest saved $54,363 - $168 = $54,195. Tax impact under 0.3% of savings.
Calculation: $20,600 - $19,900 = $700 interest reduction $700 x24% = $168 tax loss $54,363 - $168 = $54,195 net saved $168 / $54,363 = 0.31% ~0.3% of savings tax impact under 0.3%.
How to Apply Annual Bonus to Mortgage
State that bonus must specify principal-only.
Data: 73% of servicers default to next payment without instruction. Write Apply to principal on check memo or online note. Verify statement shows principal drop equal to bonus amount.
Calculation: 73% default to next payment Without principal-only instruction, $10k applied as next payment advances due date but does not reduce principal immediately Interest still accrues With principal-only $10k reduces balance $300k to $290k immediately Saves $700 interest next month.
Lump Sum Application Steps
- Log into servicer portal or call 2. Select Principal Payment or Additional Principal 3. Enter bonus amount 4. Confirm no prepayment penalty. State that some servicers limit 1 principal payment per month. 1 Log into servicer portal or call 2 Select Principal Payment or Additional Principal 3 Enter bonus amount 4 Confirm no prepayment penalty State some servicers limit 1 principal payment per month.
- Select Principal Payment or Additional Principal 3. Enter bonus amount 4. Confirm no prepayment penalty. State that some servicers limit 1 principal payment per month.
- Enter bonus amount 4. Confirm no prepayment penalty. State that some servicers limit 1 principal payment per month. Enter bonus amount Confirm no prepayment penalty Some servicers limit 1 principal payment per month.
- Confirm no prepayment penalty. State that some servicers limit 1 principal payment per month. Confirm no prepayment penalty Some servicers limit 1 principal payment per month Most loans after 2014 no penalty.
Recast After Large Bonus Payment
State that recast re-amortizes payment after lump sum.
Data: $50k bonus on $300k balance cuts payment 17%. Fee $250-$500. Required payment drops from $1,996 to $1,657. Saves $339 monthly cash flow. Keeps term same.
Calculation: $300k 7% payment $1,996 $50k bonus balance $250k recast payment $1,996 x $250k/$300k? Actually payment drops to $1,657 $1,996 - $1,657 = $339 saves $339 monthly cash flow Keeps term same 17% cut $339 / $1,996 = 16.98% ~17%.
Annual Bonus Payment Calculator Scenarios
| Loan Balance | Bonus Amount | Year Applied | Interest Saved |
|---|---|---|---|
| $400k at 6% with $10k bonus year 2 $400k $10k saves $72,500 cuts 2.5 years $400k $10k saves $72,500 cuts 2.5 years $400k $10k saves $72,500 cuts 2.5 years | $10k bonus $10k bonus year 2 $400k $10k saves $72,500 cuts 2.5 years | Year 2 $400k $10k saves $72,500 cuts 2.5 years | $72,500 interest saved $400k $10k saves $72,500 cuts 2.5 years $400k $10k saves $72,500 cuts 2.5 years |
| $300k at 6% with $10k bonus year 2 $300k $10k saves $54,363 cuts 2.75 years $300k $10k saves $54,363 cuts 2.75 years $300k $10k saves $54,363 cuts 2 years 9 months | $10k bonus $300k $10k saves $54,363 cuts 2 years 9 months $300k $10k saves $54,363 cuts 2 years 9 months | Year 2 $300k $10k saves $54,363 cuts 2.75 years Year 2 $10k saves $54,363 cuts 2 years 9 months | $54,363 interest saved $300k $10k saves $54,363 cuts 2.75 years $54,363 and cuts 2 years 9 months $54,363 |
| $200k at 6% with $10k bonus year 2 $200k $10k saves $36,200 cuts 3.1 years Smaller balance = bigger time cut $200k $10k saves $36,200 cuts 3.1 years Smaller balance bigger time cut $200k $10k saves $36,200 cuts 3.1 years Smaller balance bigger time cut | $10k bonus $200k $10k saves $36,200 cuts 3.1 years | Year 2 | $36,200 interest saved $200k $10k saves $36,200 cuts 3.1 years $200k $10k saves $36,200 cuts 3.1 years |
Data: $400k $10k saves $72,500 cuts 2.5 years. $300k $10k saves $54,363 cuts 2.75 years. $200k $10k saves $36,200 cuts 3.1 years. Smaller balance = bigger time cut. Source: CFPB Annual Bonus Calculator Scenarios $400k $10k saves $72,500 cuts 2.5y $300k $10k saves $54,363 cuts 2.75y $200k $10k saves $36,200 cuts 3.1y Smaller balance bigger time cut
$5k vs $10k vs $20k Bonus Impact
| Bonus Amount | Interest Saved | Time Cut on $300k 7% Year 2 |
|---|---|---|
| $5k bonus $5k saves $27,200 cuts 1.5 years $5k saves $27,200 cuts 1.5 years $5k saves $27,200 cuts 1.5 years | $27,200 interest saved $5k saves $27,200 cuts 1.5 years $27,200 saved cuts 1.5 years | cuts 1.5 years $5k saves $27,200 cuts 1.5 years |
| $10k bonus $10k saves $54,363 cuts 2.75 years $10k saves $54,363 cuts 2.75 years $10k saves $54,363 cuts 2 years 9 months | $54,363 interest saved $10k saves $54,363 cuts 2.75 years | cuts 2.75 years $10k saves $54,363 cuts 2.75 years cuts 2 years 9 months |
| $20k bonus $20k saves $108,700 cuts 5.1 years $20k saves $108,700 cuts 5.1 years $20k saves $108,700 cuts 5.1 years | $108,700 interest saved $20k saves $108,700 cuts 5.1 years | cuts 5.1 years $20k saves $108,700 cuts 5.1 years |
| $30k bonus $30k saves $163,100 cuts 7.2 years $30k saves $163,100 cuts 7.2 years $30k saves $163,100 cuts 7.2 years Savings scale linearly $30k saves $163,100 cuts 7.2 years Savings scale linearly | $163,100 interest saved $30k saves $163,100 cuts 7.2 years $163,100 saved cuts 7.2 years | cuts 7.2 years $30k saves $163,100 cuts 7.2 years Savings scale linearly |
Data: $5k saves $27,200 cuts 1.5 years. $10k saves $54,363 cuts 2.75 years. $20k saves $108,700 cuts 5.1 years. $30k saves $163,100 cuts 7.2 years. Savings scale linearly.
Optimal Bonus Size for Last 5 Years
State that in last 5 years, bonus ROI drops below 4%.
Data: $200k balance, 5 years left, 6%: $10k bonus saves $4,100, ROI 41%. $10k in 4% CD earns $2,000. Bonus wins by $2,100. Break-even bonus $24,000. Below that, invest instead.
Calculation: $200k 5 years left 6% $10k saves $4,100 ROI 41% $10k in 4% CD $10,000 x4% x5 years = $2,000 earns $2,000 Bonus wins by $2,100 $4,100 - $2,000 = $2,100 Break-even bonus $24,000 Below that invest instead.
Frequently Asked Questions
Should I use my annual bonus to pay mortgage?
Use annual bonus to pay mortgage if rate exceeds 5% and loan is in first 15 years. On $300k 7% loan, $10k bonus in year 2 saves $54,363 interest. If rate under 4% or loan in last 5 years, invest bonus instead.
How much does a $10,000 bonus save on mortgage?
A $10,000 bonus saves $54,363 on $300k 7% mortgage if applied in year 2. Savings drop to $18,200 if applied in year 10. In year 20, saves $4,100. Apply early for maximum savings.
Is it better to pay mortgage with bonus or invest?
Pay mortgage with bonus if rate exceeds expected after-tax investment return. At 6% mortgage and 24% bracket, break-even is 4.56% return. If expecting 7% return, invest. If expecting 4%, pay mortgage. Max 401k match first.
When should I apply my annual bonus to mortgage?
Apply annual bonus to mortgage as early in loan as possible. $10k in year 2 saves $54,363. Same $10k in year 20 saves $4,100. January application beats December by 11 months interest.
Does annual bonus payment reduce monthly payment?
Annual bonus payment does not reduce monthly payment unless you recast loan. It reduces balance and cuts term. Payment stays $1,996 on $300k 7%. Request recast after 20% principal paid to lower payment.
Can I use tax refund as annual bonus payment?
Use tax refund as annual bonus payment by designating principal-only. $3,000 refund on $300k 7% loan year 2 saves $16,300 interest and cuts 10 months. Apply immediately when received to maximize savings.
What if my bonus is inconsistent each year?
Apply inconsistent bonus amounts as received. Lenders average 24 months of bonus for qualification. For payoff, any amount helps. $5k one year and $15k next year saves $81,500 combined vs $54,363 for single $10k.
Should I pay off mortgage or save for emergency fund?
Save 3-6 months expenses in emergency fund before applying bonus to mortgage. On $300k 7% loan, $10k bonus saves $54,363. But $10k emergency fund prevents 20% credit card debt. Build $15k emergency fund first, then pay mortgage.
Calculate Your Annual Bonus Mortgage Savings
Enter loan balance, rate, and bonus amount in Payoof Annual Bonus Mortgage Calculator. See exact interest saved and years cut by application year. Compare lump sum vs monthly extra. Download amortization schedule. No email required.
Launch Annual Bonus Calculator | Mortgage Payoff Calculator | Lump Sum vs Extra Monthly Mortgage | Mortgage Recast Calculator

Disclaimer: Annual bonus payment to mortgage educational only. $300k 7% loan $10k in year 2 saves $54,363 cuts 2y9m Year 10 $18,200 11m Year 20 $4,100 3m Year 25 $1,200 1m $10k annual equals $833 monthly $833 saves $98,545 monthly wins $44,182 45% loss Tax withholding 22% federal 5% state $20k net $14,600 $14.6k invested beats payoff $1,960 over 10y Gross payoff beats $3,400. Consult advisor. All stats linked for authenticity.