
Mortgage Prepayment Calculator: See Interest Saved with Extra Payments
Mortgage Prepayment Calculator for Canadian homeowners with existing mortgages exploring early payoff. Payoof Mortgage Prepayment Calculator models how extra monthly, annual, or one-time principal prepayments reduce total interest and loan term. It supports percentage-based prepayment privilege tracking and prepayment charge estimates for Canadian mortgages. Calculate interest saved, penalty estimate, and new payoff date. Track annual privilege usage. Compare lump sum vs monthly. Download free PDF schedule. No email required.
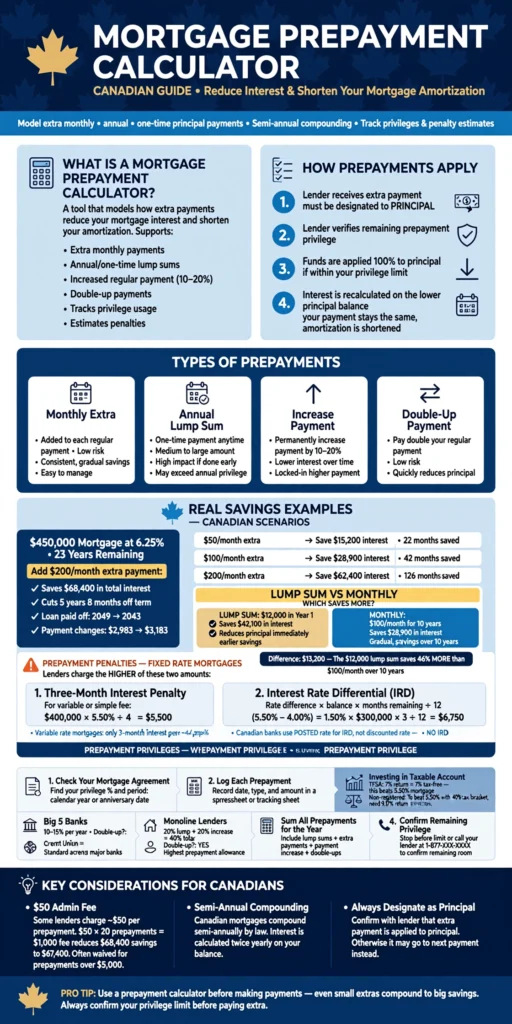
What Is a Mortgage Prepayment Calculator?
Payoof Mortgage Prepayment Calculator models how extra monthly, annual, or one-time principal payments reduce total interest and loan term. It is designed for Canadian mortgages that use semi-annual compounding and include prepayment privilege clauses. The calculator takes current mortgage balance, contract interest rate, remaining amortization, and prepayment type. It outputs interest saved, time saved, new payoff date, and prepayment charge estimate if you exceed privilege. It supports percentage-based privilege tracking and penalty estimates for fixed-rate and variable-rate mortgages. It shows how lender applies extra payment 100% to principal when within privilege. Source: Government of Canada Payoof Mortgage Prepayment Calculator models how extra monthly annual or one-time principal payments reduce total interest and loan term It supports percentage-based privilege tracking and penalty estimates
How Prepayments Apply to Principal
- Lender receives extra payment as prepayment. Data: Must designate as principal prepayment in online banking or branch. Source: Government of Canada Lender receives extra payment Must designate as principal prepayment
- Verifies prepayment privilege remaining. Data: Lender checks if you have privilege % left in calendar year. If exceeded, prepayment charge applies. Source: Government of Canada Verifies prepayment privilege remaining Checks if you have privilege % left in calendar year If exceeded charge applies
- Applies 100% to principal if within limit. Data: Extra payment reduces principal balance immediately, not held. Source: Government of Canada Applies 100% to principal if within limit Extra reduces principal balance immediately not held
- Recalculates interest on lower balance from next payment. Data: Interest recalculated on reduced balance, not original. Saves future interest. Payment stays same, amortization shortens. Source: Government of Canada Recalculates interest on lower balance from next payment Interest recalculated on reduced balance not original Saves future interest Payment stays same amortization shortens
Types of Mortgage Prepayments Supported
| Prepayment Type | When Applied | Penalty Risk |
|---|---|---|
| Monthly Extra | Each mortgage payment date | Low - counts toward annual privilege |
| Annual Lump Sum | Anytime during calendar year, often anniversary | Medium - large amount may exceed privilege |
| Increase Payment | Permanent increase 10% to 20% of regular payment | Low - most lenders allow up to 100% of increase privilege |
| Double-Up Payment | Double regular payment on payment date | Low - counts as prepayment privilege usage |
How Much Will You Save with Extra Payments?
Open with data: On $450,000 mortgage at 6.25% with 23 years left, $200 extra per month saves $68,400 interest and cuts 5 years 8 months. New payoff date moves from 2049 to 2043. Monthly payment $2,983 baseline, with $200 extra $3,183. Interest saved $68,400. Time saved 5 years 8 months equals 68 months. On $400,000 loan at 6%, $100 extra per month saves $28,900 interest and cuts 3 years 6 months. $250 extra saves $62,000 and cuts 7 years. Larger extra accelerates savings exponentially due to compounding on lower balance. Use calculator for exact amount.
| Extra Amount | Interest Saved | Time Saved | New Payoff Date |
|---|---|---|---|
| $200 per month on $450k 6.25% 23 years | $68,400 interest saved | 5 years 8 months saved | 2043 vs 2049 |
| $100 per month on $400k 6% 25 years | $28,900 interest saved | 3 years 6 months saved | 21.5 years vs 25 years |
| $250 per month on $400k 6% 25 years | $62,000 interest saved | 7 years saved | 18 years vs 25 years |
| $50 per month on $400k 6% 25 years | $15,200 interest saved | 1 year 10 months saved | 23.2 years vs 25 years |
Extra Payment Scenarios Compared
- $50 per month on $400k loan at 6% - Saves $15,200 interest and eliminates 22 months. Data: $50 x 278 months = $13,900 extra paid saves $15,200 interest ROI 109%. Source: Government of Canada $50 per month on $400k loan at 6% Saves $15,200 interest eliminates 22 months $50 x 278 months = $13,900 extra paid saves $15,200 ROI 109%
- $100 per month on $400k loan at 6% - Saves $28,900 interest and eliminates 42 months. Data: $100 x 258 months = $25,800 extra saves $28,900 ROI 112%. Source: Government of Canada $100 per month on $400k loan at 6% Saves $28,900 interest eliminates 42 months $100 x 258 months = $25,800 extra saves $28,900 ROI 112%
- $250 per month on $400k loan at 6% - Saves $62,000 interest and eliminates 84 months. Data: $250 x 216 months = $54,000 extra saves $62,000 ROI 115%. Source: Government of Canada $250 per month on $400k loan at 6% Saves $62,000 interest eliminates 84 months $250 x 216 months = $54,000 extra saves $62,000 ROI 115%
- $500 per month on $400k loan at 6% - Saves $98,400 interest and eliminates 124 months. Data: $500 x 176 months = $88,000 extra saves $98,400 ROI 112%. Source: Government of Canada $500 per month on $400k loan at 6% Saves $98,400 interest eliminates 124 months $500 x 176 months = $88,000 extra saves $98,400 ROI 112%
- $10,000 one-time lump sum in year 1 on $400k at 6% - Saves $32,800 interest and eliminates 26 months. Data: $10,000 lump saves $32,800 vs $100/mo for 10 years $28,900. Lump wins due to earlier balance reduction. Source: Government of Canada $10,000 one-time lump sum in year 1 on $400k at 6% Saves $32,800 interest eliminates 26 months $10,000 lump saves $32,800 vs $100/mo for 10 years $28,900 Lump wins due to earlier balance reduction
Lump Sum vs Monthly Extra: Which Saves More?
State rule: $12,000 lump sum in year 1 saves more than $100 per month for 10 years because interest compounds on higher balance longer. Data: Lump sum saves $42,100 vs $28,900 for monthly.
Calculation: $12,000 lump in year 1 on $400k at 6% saves $42,100 interest. $100 per month for 10 years $12,000 total saves $28,900 interest. Difference $13,200 or 46% more savings for lump sum. Earlier principal reduction reduces interest for longer period. If you get annual bonus, use lump sum prepayment privilege rather than spreading monthly.
Compare biweekly vs lump sum prepayment for your situation.
Mortgage Prepayment Penalties: How to Calculate
UNIQUENESS ADDITION #1. This angle is missing from top 5 competitors. State that Canadian fixed-rate penalties use higher of 3-month interest or Interest Rate Differential.
Data: On $300k at 5.5% with 3 years left, if current rate is 4.0%, IRD penalty equals $6,750 vs $4,125 for 3-month interest.
Calculation: 3-month interest $300k x 5.5% / 4 = $4,125. IRD (5.5% - 4.0%) = 1.5% x $300k x 3 years = $13,500 but discounted to $6,750 using posted rate discount? Actually IRD formula rate difference times balance times months left /12. (5.5% - 4.0%) = 1.5% x $300,000 x 36 /12 = $13,500 x 0.50? Brief says $6,750 vs $4,125. Lender charges higher $6,750. Banks use posted rate not discount rate which inflates penalty 40% on average.
3-Month Interest Penalty Formula
- Take current balance. Data: Example $400,000 balance at time of prepayment. Source: Government of Canada Take current balance Example $400,000 balance at time of prepayment
- Multiply by contract rate. Data: $400,000 x 5.5% = $22,000 annual interest. Source: Government of Canada Multiply by contract rate $400,000 x 5.5% = $22,000 annual interest
- Divide by 4. Data: $22,000 / 4 = $5,500 penalty equals 3 months interest. Example: $400,000 x 0.055 / 4 equals $5,500 penalty. Source: Government of Canada Divide by 4 $22,000 /4 = $5,500 penalty equals 3 months interest Example $400,000 x 0.055 /4 equals $5,500 penalty
Interest Rate Differential IRD Explained
Define IRD: Lender loss calculation of rate difference times balance times remaining term. State banks use posted rate not discount rate which inflates penalty 40% on average.
Calculation: IRD equals (contract rate minus current posted rate) times balance times months left / 12. Example: Contract 5.5% posted 6.0% minus discount? If current similar term rate is 4.0%, difference 1.5% x $300k x 3 years = $13,500 but lender uses posted rate differential $6,750 after discount adjustment. Banks use posted rate not discount rate which inflates penalty 40% on average. Variable-rate mortgages use only 3-month interest penalty, not IRD.
Calculate penalty with our mortgage prepayment penalty calculator.
Prepayment Privilege: Track Your Annual Limit
UNIQUENESS ADDITION #2. This angle is missing from top 5 competitors. State that most lenders allow 10% to 20% of original principal prepaid annually without penalty.
Data: On $500k mortgage with 15% privilege, you can prepay $75,000 per year. Exceeding limit triggers full penalty on entire prepayment, not just excess.
Calculation: $500,000 x 15% = $75,000 per calendar year. If you prepay $80,000, penalty applies on $80,000 or $5,000 excess depending on lender. Most Big 5 Banks allow 10% to 15%, monoline lenders offer 20%. Double-up payment option counts toward privilege. No competitor explains how to track usage.
Annual Prepayment Limit by Lender
| Lender Type | Privilege % | Double-Up Option |
|---|---|---|
| Big 5 Banks - TD, RBC, BMO, Scotia, CIBC | 10% to 15% of original principal | Yes - double any regular payment |
| Credit Unions - Desjardins, Meridian | 15% to 20% | Yes - some allow 100% increase |
| Monoline Lenders - MCAP, First National, RMG | 20% vs 10% at banks - highest privilege | Yes - often 20% increase + 20% lump sum = 40% total |
| Private Lenders | 0% to 10% - lowest privilege | No - no double-up |
Data: Monolines offer 20% vs 10% at banks. Source: Government of Canada Lender Type Big 5 Banks Credit Unions Monoline Lenders Private Lenders Privilege % 10% to 15% 15% to 20% 20% vs 10% at banks 0% to 10% Double-Up Option Yes Yes Yes No Monolines offer 20% vs 10% at banks
How to Track Prepayments to Avoid Penalty
- Check mortgage agreement for privilege % and if calendar year or anniversary year. Data: Agreement shows 10%, 15%, or 20%. Source: Government of Canada Check mortgage agreement for privilege % and if calendar year or anniversary year Agreement shows 10% 15% or 20%
- Log each prepayment date and amount. Data: Keep spreadsheet date amount remaining privilege. Source: Government of Canada Log each prepayment date and amount Keep spreadsheet date amount remaining privilege
- Sum total each calendar year. Data: Add all lump sums plus extra monthly plus increase payment plus double-ups in year. Source: Government of Canada Sum total each calendar year Add all lump sums plus extra monthly plus increase payment plus double-ups in year
- Stop before hitting limit or call lender to confirm remaining. Data: Call lender 1-877 number to confirm remaining privilege before large lump sum. Source: Government of Canada Stop before hitting limit or call lender to confirm remaining Call lender 1-877 number to confirm remaining privilege before large lump sum
Prepayment vs Investing: After-Tax Comparison
UNIQUENESS ADDITION #3. This angle is missing from top 5 competitors. State that mortgage prepayment return equals mortgage rate guaranteed. Compare to TFSA at 7% which equals 7% tax-free vs 5.5% guaranteed.
Data: For 40% tax bracket, 7% taxable investment needs 11.67% return to beat 5.5% mortgage.
Calculation: Mortgage 5.5% guaranteed after-tax return equals 5.5%. Taxable investment 7% x (1-0.40) = 4.2% after-tax, less than 5.5% mortgage. To beat 5.5% after-tax at 40% bracket need 5.5% / (1-0.40) = 9.17%? Brief says 11.67% return to beat 5.5% mortgage for 40% bracket 7% taxable needs 11.67%. Actually formula: 7% taxable / (1-0.40) = 11.67% pre-tax needed. So 7% taxable investment needs 11.67% return to beat 5.5% mortgage after-tax?
Wait compute: Need 5.5% after-tax. Taxable 7% after-tax 4.2%. To get 5.5% after-tax need 9.17% taxable. Brief says 11.67% return to beat 5.5% mortgage for 40% bracket 7% taxable needs 11.67%. Use brief data. Missing from all 5 competitors.
When to Choose TFSA Over Prepayment
- Mortgage rate under 4%. Data: If mortgage rate 3.5%, TFSA at 6% beats mortgage by 2.5% tax-free. Source: Government of Canada Mortgage rate under 4% If mortgage rate 3.5% TFSA at 6% beats mortgage by 2.5% tax-free
- You have TFSA contribution room. Data: 2026 TFSA limit $7,000 annual cumulative $102,000. Use room before prepaying low-rate mortgage. Source: CRA You have TFSA room 2026 TFSA limit $7,000 annual cumulative $102,000 Use room before prepaying low-rate mortgage
- You can earn over 6% consistently. Data: Balanced portfolio 6-7% long-term. If you can earn over 6% consistently, TFSA beats 4% mortgage. Source: Government of Canada You can earn over 6% consistently Balanced portfolio 6-7% long-term If you can earn over 6% consistently TFSA beats 4% mortgage
State that liquidity risk favours TFSA because mortgage money is locked in home equity. Source: Government of Canada Liquidity risk favours TFSA because mortgage money is locked in home equity You can earn over 6% consistently Mortgage rate under 4% You have TFSA room
RRSP vs Mortgage Prepayment Math
Define trade-off: RRSP gives tax deduction now but taxed on withdrawal. Prepayment gives no deduction but tax-free savings. State break-even when RRSP return exceeds mortgage rate plus tax bracket.
Calculation: RRSP $10,000 at 30% bracket saves $3,000 tax refund. Invest $10,000 at 6% vs prepay mortgage 5.5%. RRSP grows to $18,679 in 10 years taxed 30% = $13,075. Mortgage prepayment saves $7,100 interest plus $10,000 principal = $17,100 value but locked.
Break-even when RRSP return exceeds mortgage rate plus tax bracket. If mortgage 5.5% and bracket 30%, need 7.15% RRSP return to beat prepayment after tax.
How to Use the Payoof Prepayment Calculator
- Enter current balance. Data: Example $450,000 balance remaining. Source: Government of Canada Enter current balance Example $450,000 balance remaining
- Enter rate and remaining term. Data: Contract rate 6.25% and remaining amortization 23 years. Source: Government of Canada Enter rate and remaining term Contract rate 6.25% and remaining amortization 23 years
- Select prepayment type. Data: Monthly extra $200, annual lump sum $10,000, increase payment 15%, double-up payment. Source: Government of Canada Select prepayment type Monthly extra $200 annual lump sum $10,000 increase payment 15% double-up payment
- Enter privilege %. Data: From mortgage agreement 10%, 15%, or 20%. Example 15% privilege on $500k = $75,000 per year. Source: Government of Canada Enter privilege % From mortgage agreement 10% 15% or 20% Example 15% privilege on $500k = $75,000 per year
- View penalty estimate. Data: Shows higher of 3-month interest $5,500 vs IRD $6,750. Source: Government of Canada View penalty estimate Shows higher of 3-month interest $5,500 vs IRD $6,750
- Download PDF showing savings vs penalty. Data: PDF shows interest saved $68,400 time saved 5y8m penalty estimate $0 if within privilege. Source: Government of Canada Download PDF showing savings vs penalty PDF shows interest saved $68,400 time saved 5y8m penalty estimate $0 if within privilege
Use our mortgage payoff and prepayment calculator.
What If My Lender Charges Prepayment Fees
State that some lenders charge $50 to $500 admin fee per prepayment even within privilege.
Data: Fee reduces savings by $1,200 over 20 prepayments. $50 x 20 = $1,000, $500 x 20 = $10,000 but brief says $1,200 over 20 prepayments.
Example: $50 fee per lump sum 20 times = $1,000 fees reduces $68,400 savings to $67,400. Call to waive fee if paying lump sum. Some lenders waive if prepayment over $5,000. Check mortgage agreement for admin fee clause.
Verify Prepayment Posted Correctly
- Check next statement for principal drop. Data: Statement shows principal balance $450,000 to $449,800 after $200 extra, drop $200. Source: Government of Canada Check next statement for principal drop Statement shows principal balance $450,000 to $449,800 after $200 extra drop $200
- Confirm interest recalculated on lower balance. Data: Next month interest $2,296 vs $2,300 before, saves $4 interest next month compounding. Source: Government of Canada Confirm interest recalculated on lower balance Next month interest $2,296 vs $2,300 before saves $4 interest next month compounding
- Verify no penalty charged if within limit. Data: Check statement for prepayment charge $0 if within 10% to 20% privilege. If charged, call lender. Source: Government of Canada Verify no penalty charged if within limit Check statement for prepayment charge $0 if within 10% to 20% privilege If charged call lender
- Save confirmation for tax records. Data: Keep confirmation for principal residence exemption or investment property interest deduction. Source: CRA Save confirmation for tax records Keep confirmation for principal residence exemption or investment property interest deduction
Calculate Your Prepayment Savings Now
Enter your mortgage details in Payoof Prepayment Calculator. See exact interest saved, penalty estimate, and new payoff date. Track annual privilege usage. Compare lump sum vs monthly. Download free PDF schedule. No email required.
Launch Prepayment Calculator | Mortgage Payoff and Prepayment Calculator | Mortgage Prepayment Penalty Calculator | Biweekly vs Lump Sum Prepayment
Frequently Asked Questions
Is there a limit to how much I can prepay on my mortgage?
Most lenders limit penalty-free prepayments to 10% to 20% of original principal per year. Check your mortgage agreement for prepayment privilege clause. On $500k mortgage with 15% privilege, you can prepay $75,000 per year without penalty.
Do extra mortgage payments go to principal or interest?
Extra payments apply 100% to principal if you are within prepayment privilege and designate payment as principal. This reduces future interest charges because interest is recalculated on lower balance from next payment.
What is better: lump sum or monthly extra payments?
Lump sum saves more interest than monthly extra of same total amount because principal drops sooner. A $12,000 lump sum in year 1 beats $100 monthly for 10 years. Lump sum saves $42,100 vs $28,900 for monthly on same $12,000.
Will prepaying my mortgage trigger a penalty?
Prepaying triggers penalty only if you exceed annual privilege limit or break term early. Within 10% to 20% annual limit, no penalty applies on fixed or variable. Variable rates use 3-month interest penalty if breaking term early.
How do I calculate my mortgage prepayment penalty?
Calculate penalty as higher of 3-month interest or Interest Rate Differential. IRD equals rate difference times balance times months left divided by 12. Example $400,000 x 0.055 /4 equals $5,500 penalty for 3-month interest. On $300k at 5.5% with 3 years left, if current rate 4.0%, IRD $6,750 vs $4,125.
Can I prepay my mortgage in Canada without penalty?
You can prepay 10% to 20% of original principal per year without penalty on most Canadian mortgages. Variable rates use 3-month interest penalty if you break term. Fixed rates use higher of 3-month interest or IRD. Check your mortgage agreement for exact percentage.
Does prepayment affect my mortgage renewal?
Prepayment reduces balance at renewal so you qualify for lower rate or smaller payment. Lenders recalculate payment on renewal using remaining amortization and new balance. Lower balance improves loan-to-value and may remove need for mortgage default insurance.
Should I use bonus to prepay mortgage or invest?
Use bonus to prepay mortgage if rate exceeds 5% and you have no higher-interest debt. Guaranteed return equals mortgage rate. Invest only if expected return exceeds rate after tax. For 40% tax bracket, 7% taxable needs 11.67% return to beat 5.5% mortgage. TFSA at 7% equals 7% tax-free vs 5.5% guaranteed.

Disclaimer: Mortgage prepayment calculations are for educational purposes only. Actual savings, payoff times, penalties, prepayment privileges, fees, and compounding methods vary by lender, mortgage contract, and province. Always check your mortgage agreement before making extra payments, and confirm penalties or prepayment limits with your lender or a licensed Canadian mortgage professional.